
Names and identifying details in this case study have been changed to protect our client’s privacy.
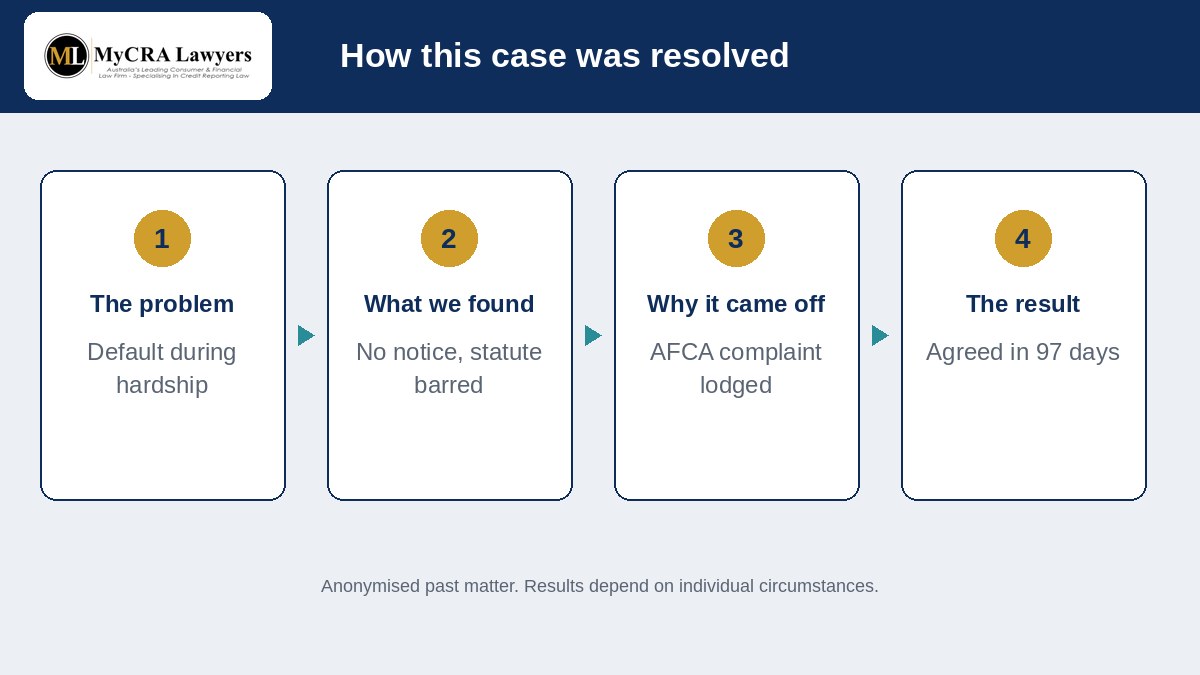
Debra was already struggling when things got worse. She was in financial hardship, she’d asked her mortgage lender, Bluestone Mortgages, for copies of her loan documents, and she believed she was being charged a variable rate on a loan that was meant to be fixed.
Then Bluestone listed a default against her for a very large mortgage debt. She spotted it through her own Equifax subscription.
A default that didn’t sit right
Debra felt strongly that she wasn’t liable for what the lender was claiming. The lender’s position was simple. It would only remove the listing if she settled the account.
What we did
We took it to the Australian Financial Complaints Authority and argued three grounds. First, she hadn’t been given notice that the lender intended to list a default. Second, she was in financial hardship when it happened. Third, we argued the debt was statute barred, meaning the time for the lender to enforce it had run out.
Why it came off
Then AFCA told us the lender had advised that the default listing would be removed. No payment, no settlement. The lender’s demand that she settle first had fallen away.
The result
Bluestone agreed to remove the default 97 days after our first request.
Agreeing and doing are two different things, though. The lender was slow to act on its promise. We kept chasing, and kept chasing, until the default was finally gone from Debra’s file.
What this means for you
“Pay up or it stays” is a negotiating position, not the law. If there are real problems with how a default was listed, a complaint can get it removed without paying to make it go away. And if a creditor agrees but drags its feet, someone needs to hold it to its word. Our credit repair lawyers do exactly that.
This is a past matter. Names and identifying details have been changed to protect our client’s privacy.
Results depend on individual circumstances. Every credit file is different, and a past result doesn’t guarantee the outcome of your matter. This case study is general information, not legal advice.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
MyCRA Lawyers | Australia-wide | 1300 667 218 | Contact form | Book a 15-minute intro call

Leave A Comment