
Updated 17 November 2026. By Graham Doessel.
Short answer
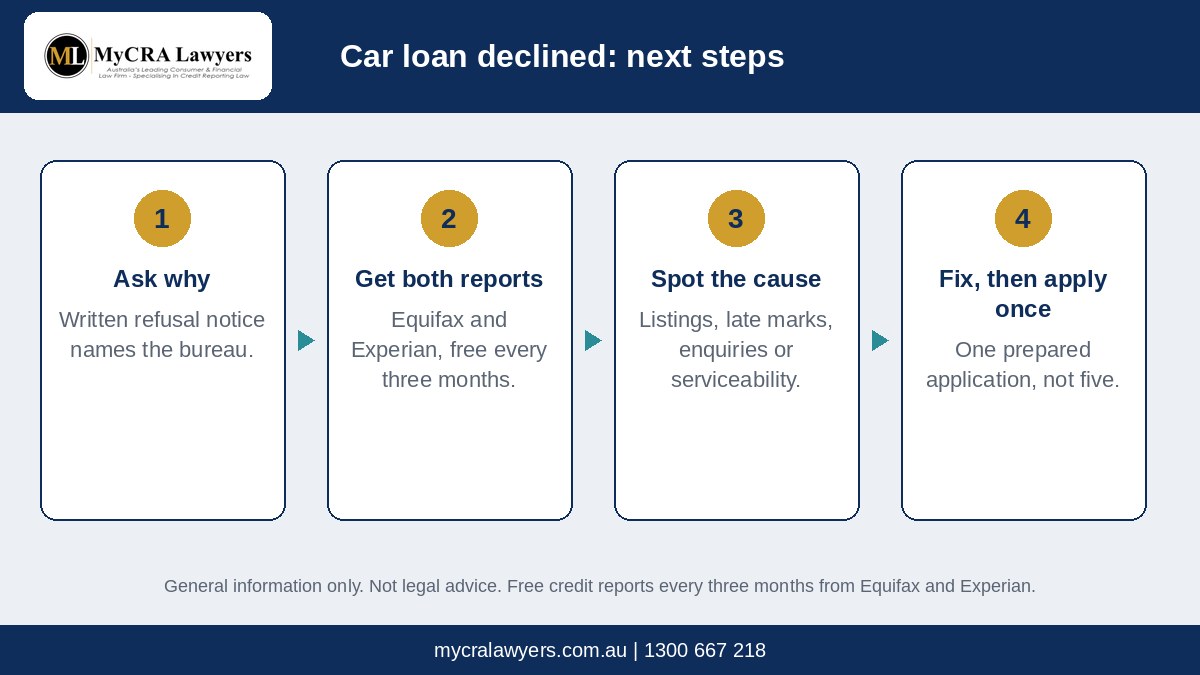
If a lender refuses your car loan wholly or partly because of your credit report, the Privacy Act requires it to tell you in writing and name the credit reporting bureau it used. Start by asking the lender for that notice and for its reasons. Then get your reports from Equifax and Experian. Australians can get a free report from each every three months, and after a refusal it is worth asking about free access linked to that decision. Look for defaults, court judgments, late repayment marks, identity errors and a cluster of recent enquiries, which dealership finance can create if your application goes to several lenders. Many declines are about serviceability (income, expenses and existing limits) rather than the credit file. Don’t reapply straight away. Fix any errors first, or the next attempt will simply add another enquiry.
Hi, I’m Graham. Car finance knock-backs hurt in a particular way. You’ve picked the car, the salesperson is keen, and then the finance manager comes back with bad news. The usual reaction is to try somewhere else that afternoon. That is the most expensive move you can make, because every new application can add another enquiry to a file that is already struggling. Slow down for a fortnight and find out what actually happened.
Why do car loans get declined?
Lenders don’t always explain their scorecards, but declines usually come down to a few things:
- Credit file listings: defaults, court judgments, serious credit infringements or personal insolvency
- Repayment history: recent late marks on loans or cards, even without a default
- Enquiry patterns: several credit applications in a short period, including BNPL and payday-style products
- Serviceability: income, living expenses and existing commitments, including the full limits on credit cards and BNPL accounts
- Identity mismatches: addresses, names or dates of birth that don’t match across the application and the file
- Stability and policy: how long you’ve been in your job or at your address, residency status, or the age and type of vehicle
Only some of these can be fixed through your credit file. Knowing which one caused the decline saves you from fixing the wrong thing.
Can you find out whether your credit file caused the decline?
Often, yes. Under section 21P of the Privacy Act, if a credit provider refuses an application for consumer credit based wholly or partly on credit information from a credit reporting bureau, it must give you written notice. The notice must say the refusal was based on that information and name the bureau.
Ask the lender, or the dealer or broker who arranged the application, for:
- the written refusal notice
- which bureau the lender used
- whether the decline was about the credit file, serviceability or lender policy
Lenders don’t always give detailed reasons, but asking costs nothing. Our guide on what to do after a credit refusal covers this step in more detail.
How do you get your credit reports after a knock-back?
Request your consumer credit report from both Equifax and Experian. You are entitled to a free report from each every three months. illion’s consumer bureau has been absorbed into Experian, so those two cover the consumer bureaus. Download and save the PDFs. A score in an app isn’t enough, because lenders read the listings behind the number. See how to get your free credit report.
What should you look for first?
- Defaults and judgments. Check the creditor, amount, listing date and status on each.
- Repayment history. Look for any month showing a 1 or higher in the last two years.
- Enquiries. How many in the last few months, from whom, and do you recognise them all?
- Identity data. Are there addresses you never lived at, or a name spelt differently?
- Differences between bureaus. Some lenders report to only one bureau, so the two files rarely match exactly.
Once you have both PDFs, you can upload them for a free credit file analysis at app.FixMyBadCredit.com.au to get a structured read of what is on the file.
Did the dealership apply to several lenders at once?
This happens a lot. When you sign the dealership’s finance paperwork, you may consent to your application going to more than one lender. Each lender that runs a full credit check can record an enquiry. Several finance enquiries close together can look like credit-seeking to the next lender’s scorecard.
Before you sign anything next time, ask:
- How many lenders will this application go to?
- Will a credit enquiry be recorded before I’ve accepted a quote?
- Can you give me an indicative rate before a full application?
If an enquiry on your file was made without your consent, it may be removable. Enquiries you agreed to, even ones you now regret, usually aren’t. See when a credit enquiry can be removed.
What can you fix before you reapply?
- Errors: dispute inaccurate defaults, wrong amounts, unauthorised enquiries and identity mix-ups in writing with the credit provider. Escalate to AFCA or the OAIC if needed.
- Unused limits: lenders often assess the full limit, not the balance, so reducing or closing unused credit cards and BNPL accounts can help serviceability.
- Current conduct: pay every account on time. A payment more than 14 days late can be reported as missed.
- Your story: if there was a one-off event, such as illness or a job change, write a short, factual explanation a broker can pass on.
If a default looks non-compliant, our default removal page explains what we check.
Should you take a higher-rate “bad credit” car loan instead?
Sometimes it’s the right call if you genuinely need a car for work. Compare the total cost, not just the weekly repayment. ASIC’s Moneysmart website has a free car loan calculator. Be wary of any offer that seems to approve anyone. And if the decline was caused by an error on your file, fixing it first could save you a lot in interest over the life of the loan.
How long should you wait before applying again?
There’s no fixed rule. A sensible approach is to wait until you know why you were declined and have fixed anything that can be fixed. Then make one well-prepared application through a single broker or lender. If you’re working through disputes, wait until both bureau reports show the corrections.
How can MyCRA Lawyers help?
If a car loan decline has left you unsure what is on your file, email both bureau reports and the lender’s refusal notice. We will tell you whether there is anything worth disputing before your next application.
MyCRA Lawyers is a specialist credit repair law firm. Have your Equifax and Experian report PDFs ready and reach us through our contact form, call 1300 667 218 or 07 3124 7133, or book a 15-minute credit repair intro call. Postal: PO Box 169, Aspley QLD 4034. We quote fixed fees in writing after we assess the file, and we will tell you plainly if a listing looks like a wait-out rather than a viable dispute. On consumer defaults accepted after initial assessment, our independently audited success rate is 91.6%. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. No law firm can promise every listing will come off, and we don’t.
Not ready to talk yet? Pull both free reports and start with a free credit file analysis at app.FixMyBadCredit.com.au. For the bigger picture of how listings are challenged, read our credit repair lawyers Australia guide.
Frequently asked questions
Does a declined car loan show on my credit file?
The decline itself isn’t usually listed, but the application can record a credit enquiry. Several enquiries close together can affect how later lenders view you.
Does a lender have to tell me why it refused my car loan?
If the refusal was based wholly or partly on information from a credit reporting bureau, the lender must give you written notice saying so and name the bureau. Detailed reasons beyond that vary by lender.
How do I get a free credit report after a car loan refusal?
You can get a free report from Equifax and from Experian every three months. After a refusal, also ask the bureau about free access linked to that decision.
Can dealership finance put multiple enquiries on my file?
It can, if your application goes to several lenders and each one runs a credit check. Ask how many lenders will see the application before you sign the consent.
Can I remove enquiries from car finance applications?
Only in limited cases, such as an enquiry made without your consent or an error. Enquiries you genuinely agreed to usually stay on the file.
General information only. Not legal advice for your circumstances. Liability limited by a scheme approved under Professional Standards Legislation.

Leave A Comment