
Updated 9 October 2026. By Graham Doessel.
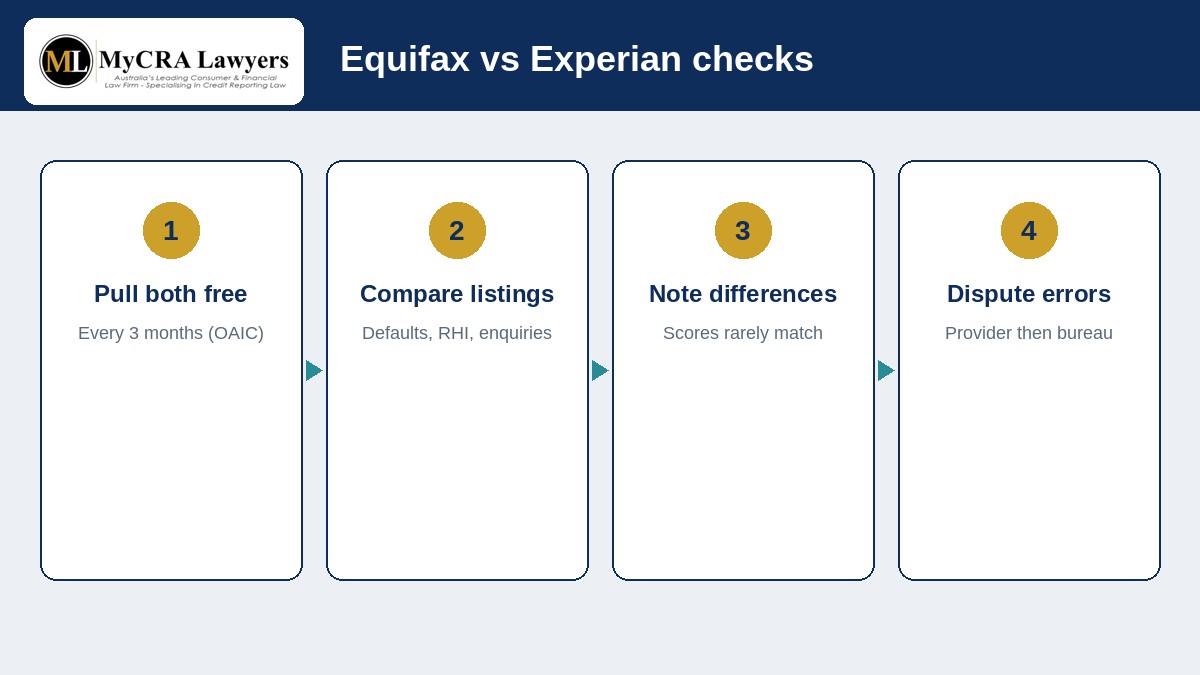
Australians can get free consumer credit reports more often than most people think. Under Australian credit reporting rules, a credit reporting body must give you a free consumer credit report once every three months (OAIC). You can also request a free copy after a credit refusal within the past 90 days, or after a correction. Get both. Then check identity details, defaults, enquiries, judgments and repayment history before you apply for a home loan or dispute anything.
Hi, I’m Graham. The fastest way into Credit Prison is not knowing you are already there. I have lost count of the good, honest Australians who only discover a default when a broker’s email lands with a decline. Free reports exist for a reason. Use them before you apply, not after.
Your legal right to access credit information
Under the Privacy Act 1988 and the Privacy (Credit Reporting) Code, credit reporting bodies and credit providers have obligations around access to your credit reporting information. In day-to-day terms, that means you can request your file from each major bureau and you should not have to buy a paid subscription just to see what lenders see.
Paid monitoring products are optional extras. They can alert you to changes. They are not required for a one-off cleanup. Our explainer on free vs paid credit reports covers the trade-offs.
How to request each bureau’s free report
Processes and portals change, so treat this as a map, not a screenshot tutorial. As of writing, Australia has two consumer credit reporting bodies (Equifax and Experian). Experian absorbed illion’s consumer bureau from 1 April 2026:
Equifax
Use Equifax’s consumer access or “my credit file” style portal (search from equifax.com.au). Complete identity verification. Download or save the full report PDF, not just the score graphic. We explain the scoring side in how credit enquiries affect your credit score.
Experian (includes former illion data)
Use Experian’s Australian consumer access options via experian.com.au (order credit report). From 1 April 2026, Experian’s consumer credit report includes information previously held separately by illion. You do not need a separate illion report. Older letters may still say “illion”; that generally refers to the new Experian file. Save the PDF.
Practical tips
- Do both in the same week so dates line up.
- Use the same identity documents each time to reduce mismatch.
- Store PDFs somewhere safe. Portal links expire.
- If a bureau charges for a product you do not need, look again for the free access option tied to Privacy Act access rights or the three-monthly free report.
After a credit application is refused, ask about free access tied to that refusal. Keep the decline email.
Checking your own file should not create a lender enquiry. See checking your credit score won’t lower it.
Red-flag checklist: what to look for first
Open the PDF and work top to bottom.
1. Identity and contact data
Wrong date of birth, old names, addresses you never lived at, or a driver’s licence that is not yours can mean file mixing. Fix identity errors early. They drive wrong listings and wrong scores.
2. Defaults
For each default note creditor, amount, list date, and paid status. Ask yourself:
- Did I get the notices?
- Was I at least 60 days overdue?
- Was the amount at least $150 for a consumer default?
- Is the amount right?
- Is this even my account?
If something looks off, read our how to remove a default guide (once published) and the service page for default removal. The full legal framework sits in our credit repair lawyers Australia cornerstone.
3. Enquiries
Clusters of payday, BNPL or car finance enquiries crush some lender scorecards. Unauthorised or incorrect enquiries may be removable. Ordinary shopping enquiries usually are not. See enquiry removal.
4. Repayment history information (RHI)
Late marks on comprehensive credit reporting can hurt even without a default. Learn what RHI means on repayment history information.
Hardship notes on the file, or financial hardship information flags, also deserve a slow read. If you asked for hardship help and a default appeared anyway, keep those emails. They can matter in a dispute.
5. Judgments and other public record style data
A judgment is not a default. It needs a different strategy. Start at judgment removal.
6. Cross-bureau mismatches
A default on one bureau only is still real for lenders who use that bureau. Compare both. Our Equifax vs Experian guide explains why scores diverge and what happened to illion.
What to do when you find a problem
- Write to the credit provider that disclosed the information. Attach evidence.
- Use the bureau dispute process where required.
- Diary the investigation timeframes under the Credit Reporting Code.
- Escalate to AFCA if the firm is a member and the response is inadequate (free for consumers).
- Consider OAIC for credit reporting privacy complaints.
- Get legal help if the creditor digs in, the notices are contested, or a loan deadline is close.
MyCRA Lawyers can review both files with you. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees quoted in writing. Selected consumer default work includes a Money Back Guarantee on the published terms.
Before you apply for a home loan
Brokers see the same pattern constantly: clients apply first, check the file second. Flip that order.
Two weeks before you lodge:
- Pull both free reports (Equifax and Experian)
- Dispute anything clearly wrong
- Avoid new finance enquiries (including “just checking” car yards and BNPL)
- Tell your broker about every default and judgment up front
If a listing needs a legal audit, start that before the contract dates get tight. Removal timelines vary. Some accepted defaults move in days; escalations can take months. Planning beats panic.
Send us your file for an assessment
If you already have the PDFs, email docs@mycralawyers.com.au or book a 15-minute credit repair intro call. Call 1300 667 218 if you prefer to talk it through. If we think your chances are low, we will say so.
Free support outside a law firm still matters: free bureau access, free AFCA complaints, OAIC, and the National Debt Helpline on 1800 007 007 for hardship and budgeting.
Credit Prison starts with a PDF you never opened
Most people we help could have seen the problem months earlier. The reports are available. The law gives you access. The hard part is reading them with a clear checklist and then acting. We explain how our process works before you commit to anything.
Do that this week, before the next application.
Next step: free credit file analysis
Reports in hand? Don’t leave them sitting in Downloads.
Get a free credit file analysis at app.fixmybadcredit.com.au: upload the Equifax or Experian file that shows the problem (or ask us to obtain it), answer a few questions about your situation, and get plain-English next steps. Full walkthrough: You’ve got your free credit reports, now what?.
FAQ
How often can I get a free credit report in Australia?
A credit reporting body must give you a free consumer credit report once every three months (OAIC guidance on access to your credit report). You can also request a free copy if you have been refused credit within the past 90 days, or if your credit-related personal information has been corrected. Confirm the current request path on each bureau’s site.
Is a free report the same as a credit score app?
Not necessarily. You want the full credit reporting information (listings and details), not only a score dial. Apps vary in what they show and which bureau they mirror.
Will requesting my own report lower my score?
Accessing your own credit reporting information is not treated like a lender credit enquiry. Lender enquiries are different.
Which bureau should I start with?
Start with either, finish with both Equifax and Experian. If you know your broker’s target lender uses one bureau, still check the other before you celebrate.
Can MyCRA get the reports for me?
Yes. As part of onboarding we can obtain Equifax and Experian information for assessment (Experian includes former illion data). Bring your own PDFs if you already have them.
This is general information, not legal advice. Bureau portals and free-access rules change. Verify current steps on each CRB website. Liability limited by a scheme approved under Professional Standards Legislation.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | Book a 15-minute intro call

Leave A Comment