
Names and identifying details in this case study have been changed to protect our client’s privacy.
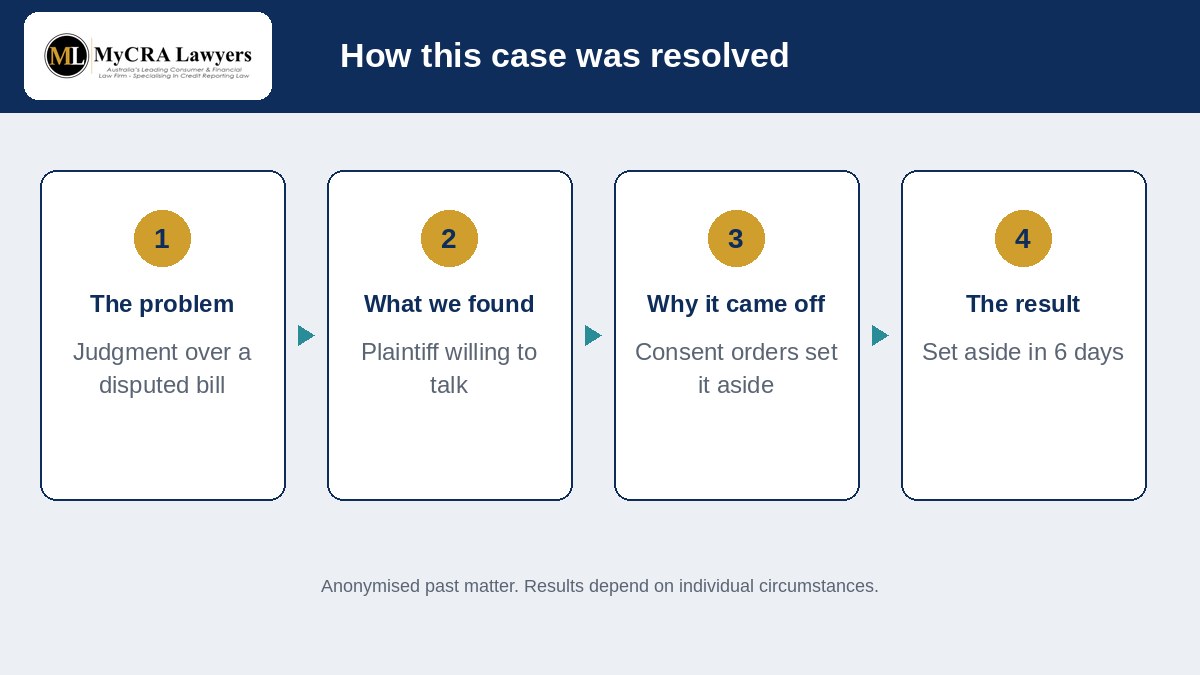
There’s a particular kind of frustration in getting a court judgment from the people who were supposed to be helping you. That’s where Greg landed.
Greg and his wife wanted to apply for finance. Their broker spotted a judgment on Greg’s credit file for about $26,000. The plaintiff was a law firm he’d once used.
How it happened
The firm had acted for Greg in a dispute over unpaid work and the end of his role as a company director, a period where he lost a lot of money. In his view, they handled it badly. He ended up moving to other lawyers.
Then came the bill. Greg disputed the charges more than once. Every time he asked to talk them through, he was told nobody could “find time in the diary”. Eventually he gave up chasing. The firm went to court instead, and the judgment followed.
Why a judgment is worse than a default
Lenders treat court judgments very seriously. A judgment tells them a creditor went all the way to court and won. For a couple trying to borrow, it’s close to a deal killer.
What we did
The plaintiff responded quickly once we were involved, which made a big difference. Greg chose to pay the outstanding amount so he could move on. On our request, the plaintiff agreed to sign consent orders setting the judgment aside.
Why it came off
A judgment that has been set aside by the court no longer stands, and the credit reporting bodies remove it from your file. Getting the other side to consent is what makes that fast. Without consent, you’re looking at a contested court application.
The result
We started on 14 February. The judgment was set aside on 20 February, 6 days later. Greg and his wife could get on with their finance application.
What this means for you
Paying a judgment debt doesn’t make the judgment disappear. Having it set aside does. If you have a judgment on your file, paid or unpaid, it’s worth asking whether the plaintiff will consent. Our credit repair lawyers handle these applications regularly.
This is a past matter. Names and identifying details have been changed to protect our client’s privacy.
Results depend on individual circumstances. Every credit file is different, and a past result doesn’t guarantee the outcome of your matter. This case study is general information, not legal advice.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | Book a 15-minute intro call



Leave A Comment