
Updated 9 October 2026. By Graham Doessel.
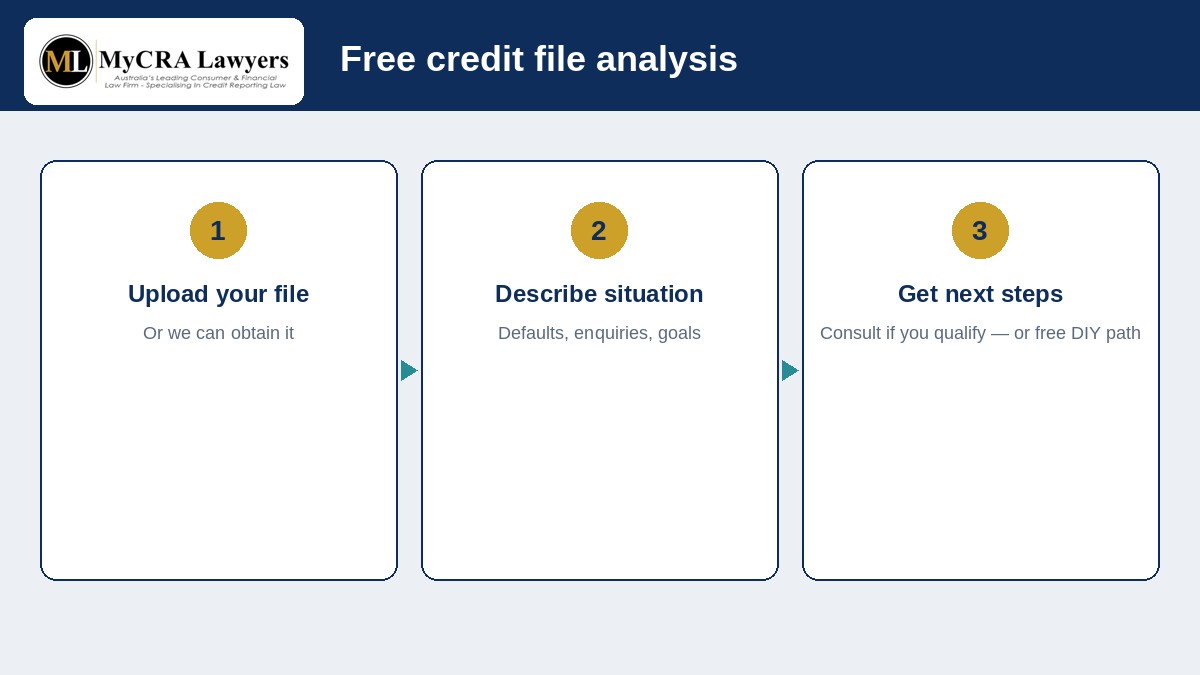
Free reports are step one. Making sense of them is step two. MyCRA’s tool at app.fixmybadcredit.com.au is built for that: create a free account, upload the credit file that shows the problem (or ask us to obtain it), answer a few questions about your situation, and get plain-English guidance on what may be holding you back and what to do next. If you qualify for legal help, you can book a consultation. If not, you still walk away with free DIY direction.
Hi, I’m Graham. Pulling the reports is step one out of Credit Prison. Reading them cold, without a checklist, is how people freeze and do nothing for another six months. The free analysis exists so you can see the blockers in English, not bureau jargon.
First: get the free reports (every three months)
Under Australian credit reporting rules, a credit reporting body must give you a free consumer credit report once every three months (OAIC, Access your credit report). You can also request a free copy after a credit refusal within the past 90 days, or after a correction.
Australia now has two mainstream consumer credit reporting bodies: Equifax and Experian. Experian absorbed illion’s consumer credit bureau; from 1 April 2026 an Experian report includes data previously held separately by illion. You do not need a separate illion report for a current cleanup.
Step-by-step: How to get your free credit report in Australia.
What the free credit file analysis is
On the public FixMyBadCredit app landing page, the offer is described as a Free Credit File Analysis: credit files are confusing on purpose, and the tool is there to read yours and show what is holding you back in plain English. It is powered by MyCRA Lawyers (Legal Practice Holdings Group).
We only describe what the public page states. We are not inventing hidden scoring engines or guarantees of removal from the upload alone.
What it looks for (the listing types named on the site)
The same public page lists the negative listing types the specialist lawyers challenge and remove where the law allows: For the full process, see our guide on how to remove a default from your credit file.
- Defaults: paid or unpaid, including banks, telcos and energy providers where proper process was not followed
- Credit enquiries: including unauthorised, duplicate or incorrectly listed enquiries (payday lender enquiries get a special mention for mortgage damage)
- Court judgments: where procedures were not followed; paid judgments may be negotiated for removal
- Late repayments (RHI): repayment history marks, especially where hardship arrangements or inaccurate reporting are involved
- Serious credit infringements
- Clearouts and cross-matches: incorrect personal information, “also known as” entries and clearouts that confuse lenders
Whether any particular listing on your file is removable depends on the facts and the Privacy Act / Credit Reporting Code rules. The analysis helps surface candidates; it is not a promise that every negative mark will come off. If you are wondering whether to wait it out, read how long a default stays on your credit file.
How the three steps work (from the public app page)
1. Upload your credit file
Create a free account and upload your Equifax or Experian credit file, whichever shows the bad credit. (The app page still mentions illion as an upload label; treat that as legacy labelling. Former illion consumer data now sits with Experian.) Don’t have a report yet? The page says we can get it for you.
2. Tell us your situation
Answer a few quick questions about your circumstances so the guidance can reflect your personal situation and goals, not a generic template letter.
3. We tell you what’s next
If you qualify, you can book a consultation with a credit repair specialist. If not, the page says you still get what you need to fix it yourself, completely free.
That last point matters. A free analysis that only exists to hard-sell is useless. Use the tool. Read the answer. Then decide.
Why this beats staring at a PDF alone
Full reports are dense. Scores without listing detail do not help a dispute. A structured pass over defaults, enquiries, judgments, RHI and identity mismatches is what turns “I think something is wrong” into a plan.
For the legal framework behind removals, see our credit repair lawyers Australia cornerstone, plus the service pages for default removal, enquiry removal, judgment removal and repayment history information.
On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Selected matters include a Money Back Guarantee on the published terms. Fixed fees are quoted in writing before you start.
Start your free analysis
- Get your free Equifax and Experian reports (every three months).
- Go to https://app.fixmybadcredit.com.au.
- Create your free account, upload the file that shows the problem (or ask us to obtain it), and answer the situation questions.
- Read the plain-English next steps. Book a consult only if it makes sense.
Prefer to talk first? Call 1300 667 218, email docs@mycralawyers.com.au, or book a 15-minute credit repair intro call. Our credit repair process is set out in plain English.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
FAQ
Is the credit file analysis really free?
The public FixMyBadCredit app page markets it as a Free Credit File Analysis. Creating an account and uploading a file for that analysis is presented as free. Legal work after you qualify is a separate engagement with fees quoted before you start.
Do I need Equifax and Experian reports before I start?
Having the PDFs ready is ideal. The app page also says that if you don’t have a credit file yet, we can get it for you. Free bureau access is available every three months (OAIC).
Will uploading my report fix my credit automatically?
No. The analysis explains what appears to be holding you back and what to do next. Removals still depend on compliance, evidence and the usual dispute or legal pathways.
What if I don't qualify for MyCRA to act?
The app page states that if you do not qualify, you still get what you need to fix it yourself, completely free. Use that guidance, AFCA where relevant, and the OAIC for credit reporting privacy complaints.
Is this the same as a paid credit-score monitoring app?
No. Monitoring apps track scores. This tool is positioned as a free analysis of what on your file is blocking you, backed by a specialist credit repair law firm.
This is general information, not legal advice. App features and bureau portals change. Confirm current steps on the live site. Liability limited by a scheme approved under Professional Standards Legislation.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | PO Box 169, Aspley QLD 4034 | Book a 15-minute intro call

Leave A Comment