
Updated 10 October 2026. By Graham Doessel.
Before you pay anyone to “fix” your file, ask harder questions. Before you hire a credit repairer in Australia, ask who owns the firm, whether they are a law practice, how fees work, what success rate they publish (and how it was audited), what happens if a listing cannot be removed, and which free options you should try first (bureau access every three months, AFCA, OAIC, National Debt Helpline). ASIC has warned about predatory credit repair for years. A specialist law firm is not the same as a letter mill.
Hi, I’m Graham. Credit Prison is bad enough without paying someone to send template letters into a black hole. These are the questions I tell friends and brokers to ask, including when they are interviewing us.
1. Are you actually a law firm?
Ask for the practice name, ABN, and how to verify them on the relevant law society register. Non-law firms cannot give legal advice the way a law practice can. Our credit repair lawyers Australia cornerstone explains why that distinction matters for defaults, enquiries and judgments.
2. What is your independently audited success rate?
Anyone can invent a percentage. Ask for the exact definition (what was counted, what was excluded). On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees quoted before you start. Selected matters include a Money Back Guarantee on the published terms.
3. Fixed fee or success fee surprises?
Get the fee in writing before work starts. Ask what is included, what triggers extras, and whether a Money Back Guarantee applies (and on what terms).
4. Will you look at Equifax and Experian?
Australia now has two mainstream consumer bureaus. Experian absorbed illion; from 1 April 2026 Experian includes former illion data. If a firm only talks about one portal score, walk away. For the full process, see our guide on how to remove a default from your credit file.
5. What free steps should I take first?
Free reports every three months (OAIC), free AFCA complaints for eligible firms, OAIC for privacy complaints, National Debt Helpline 1800 007 007. Honest operators say this out loud.
6. How do you handle matters with low prospects?
Ask whether they will tell you straight if chances are low. That is our standard on the intro call.
7. Who does the work: and how do I contact them?
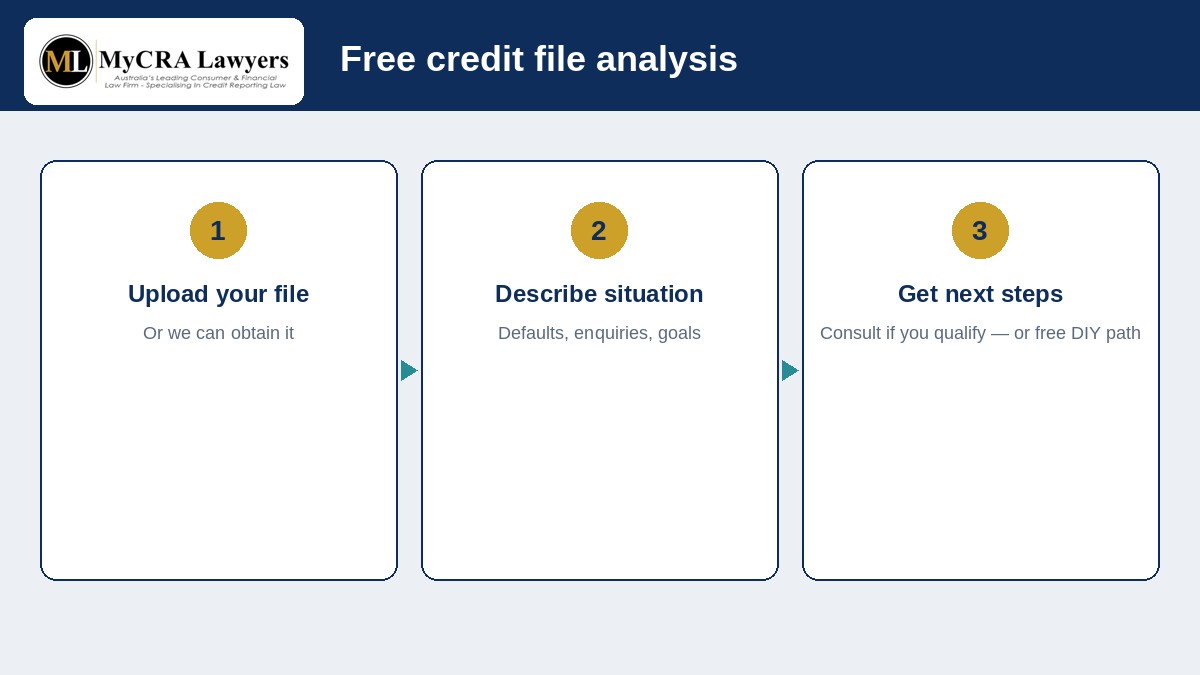
Get a direct phone number and email for documents. Ours: 1300 667 218 / 07 3124 7133 / docs@mycralawyers.com.au. Also try the free analysis at app.fixmybadcredit.com.au.
Pricing overview: how much is credit repair. Why us: why choose MyCRA.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
Questions that expose weak operators
- Who is the solicitor on the record if you advertise legal services?
- What exactly is included in the fixed fee, and what is excluded?
- How do you define the cohort behind any success rate, and who audited it?
- Will you put in writing that you do not guarantee removal on every file?
- What happens if the creditor refuses, AFCA, OAIC, or quiet ghosting?
- Do you require both Equifax and Experian PDFs before quoting?
- Where do complaints go if we disagree?
ASIC has scrutinised credit repair and payday models for years. Treat “guaranteed wipe” language as a walk-away signal. Prefer independently audited figures, written fees, and honest triage.
MyCRA Lawyers quotes fixed fees after assessment. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Selected work: Money Back Guarantee terms.
Also read is credit repair legit and the cornerstone.
Equifax and Experian: always both
Australia’s consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, so you do not need a separate illion report today. Scores rarely match. Free consumer reports are available every three months (OAIC). After a refusal, ask about free access tied to that decision. Save PDFs, not only score dials.
A simple cleanup order
- Identity and contact data
- Defaults and serious credit infringements
- Judgments
- Enquiries
- Repayment history information
- Hardship flags
Dispute clear errors before you generate new hard enquiries. For broker deals, pause lodgement until the triage is honest. Use app.fixmybadcredit.com.au for a free file analysis once you have the PDFs.
Putting it into practice this month
Start with both free Equifax and Experian consumer credit reports. Under OAIC guidance you can access a free consumer credit report from each credit reporting body once every three months, and you should also ask about free access after a credit refusal or after a correction. Save the PDFs. Compare identity details, defaults, serious credit infringements, judgments, enquiries and repayment history information side by side.
Next, write a dated chronology for anything that looks wrong: notices received or not received, hardship emails, payments, address changes, and collector contact. Send a clear written dispute to the credit provider that disclosed the information, attach your evidence, and diary the response timeframes under the Privacy (Credit Reporting) Code. Use the bureau dispute process where required. If the firm is an AFCA member and internal dispute resolution fails, AFCA is free for eligible consumers. OAIC pathways may fit some credit reporting privacy complaints. The National Debt Helpline on 1800 007 007 remains available for budgeting and hardship conversations. We explain how our process works before you commit to anything.
If a broker deadline is close, a judgment or clearout is involved, or the creditor contests the facts, get a legal triage rather than spraying new hard enquiries across lenders. Email docs@mycralawyers.com.au, call 1300 667 218, or book a 15-minute intro call. Read the full framework on our credit repair lawyers Australia cornerstone. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. Selected matters include a Money Back Guarantee on published terms. Postal address: PO Box 169, Aspley QLD 4034.
FAQ
Is credit repair legal in Australia?
Yes when work targets inaccurate or non-compliant listings under the Privacy Act and Credit Reporting Code. Guaranteed score lifts and fake success rates are red flags.
Should I use a law firm or a credit repair company?
A law practice can advise and act in ways a non-law letter service cannot. Verify registration and fee terms either way.
What is a fair success rate claim?
One that is defined clearly and independently audited. Ask for the certificate, not a marketing round number.
Do I still need both bureau reports?
Yes, Equifax and Experian. Free access every three months.
Where do I start with MyCRA?
Free analysis at app.fixmybadcredit.com.au, or book a 15-minute intro call.
This is general information, not legal advice. Liability limited by a scheme approved under Professional Standards Legislation.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | PO Box 169, Aspley QLD 4034

Leave A Comment