
Updated 27 October 2026. By Graham Doessel.
Credit repair is legitimate work when it means enforcing Privacy Act and Credit Reporting Code rights. It is also an industry ASIC has watched for years because some operators sold hope, charged like gamblers, and were not lawyers. If you are shopping for help, treat marketing claims like a credit application: verify everything.
What “legit” should mean
- Someone who can actually practise law if they claim legal services
- Written fees you understand before you sign
- No guarantee of removal on every file
- Honest triage, including “this one may need to age off”
- Independently audited results where success rates are advertised
MyCRA Lawyers is a law firm. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. We quote fixed fees in writing. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. We do not promise outcomes we cannot stand behind.
Red flags ASIC-style scrutiny taught consumers to spot
- Upfront fees with fuzzy deliverables
- “Guaranteed removal” language
- Pressure to sign before you see either bureau PDF
- No clear complaints pathway
- Success statistics with no auditor, no cohort definition, no date
Read our related pieces on questions before hiring, ASIC crackdowns, and the cornerstone credit repair lawyers Australia.
Fee models
Fixed fee: you know the price for defined workstreams.
Success / contingency style: can align incentives, can also encourage over-promising. Read the contract. There are lessons in ASIC action against credit repair businesses.
Subscription “monitoring”: optional; not a substitute for dispute work.
Pricing overview: how much is credit repair.
Free paths you should still use
Free Equifax and Experian reports every three months (OAIC). Free AFCA complaints for members. OAIC privacy pathways. National Debt Helpline 1800 007 007. A law firm should not pretend those options do not exist. For a wider view of the choices, see credit repair in Australia: understanding your options.
How to choose in one afternoon
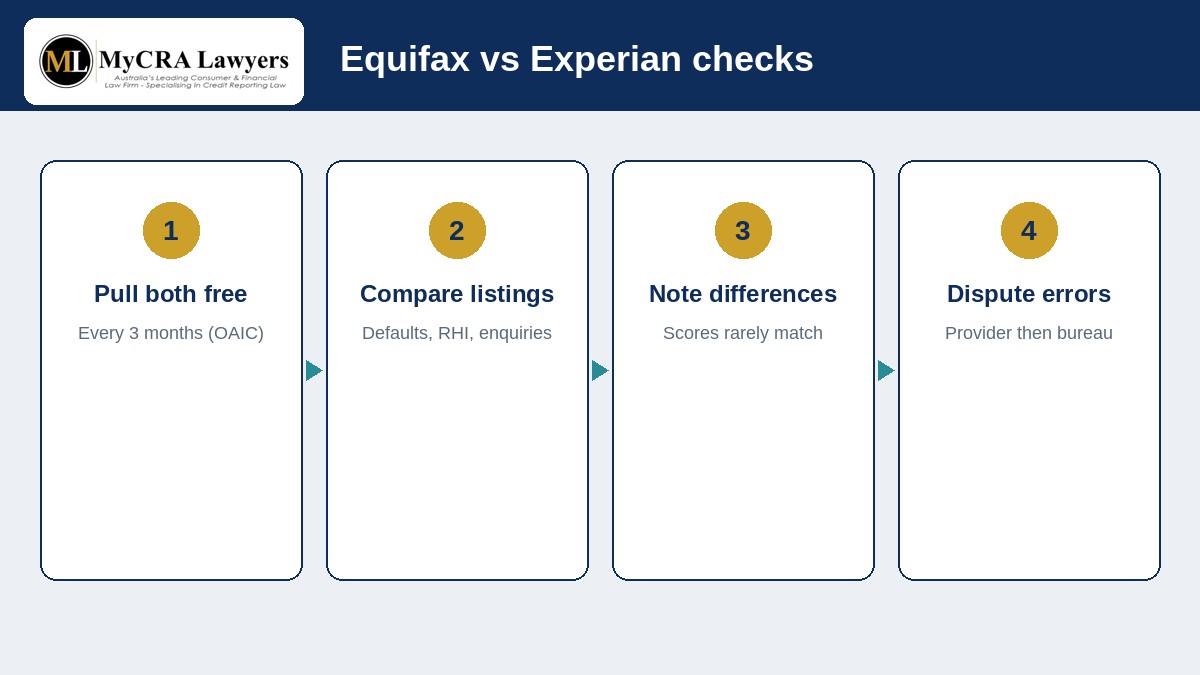
- Pull both free reports
- Run a free credit file analysis
- Shortlist firms; check QLS / practising status where legal work is claimed
- Ask for fee quotes in writing and sample engagement terms
- Book a 15-minute intro call if you want our view
Reach us through our contact form or call 1300 667 218. PO Box 169, Aspley QLD 4034.
Law firm vs “credit repair company”
Anyone can market cleanup services. Not everyone can give legal advice or run court-adjacent strategy. If a website says “legal” without a practising trail you can verify, walk.
Ask: who is the solicitor on the record? Where is the complaints policy? What happens if the dispute fails?
How we quote
We assess the PDFs first. If chances are poor, we say so. Fixed fees for defined work. That is the opposite of a hope subscription.
A one-afternoon buyer checklist
- Pull both free bureau reports
- Run free analysis
- Shortlist firms; verify practising status if legal work is claimed
- Compare written fee quotes and exclusions
- Ask how success rates are defined and audited
- Keep AFCA/OAIC/DIY options on the table
MyCRA Lawyers is a law firm. We assess PDFs before quoting. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees. No fantasy guarantees.
Equifax and Experian: always both
Australia’s consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, so you do not need a separate illion report today. Scores rarely match. Free consumer reports are available every three months (OAIC). After a refusal, ask about free access tied to that decision. Save PDFs, not only score dials.
A simple cleanup order
- Identity and contact data
- Defaults and serious credit infringements
- Judgments
- Enquiries
- Repayment history information
- Hardship flags
Dispute clear errors before you generate new hard enquiries. For broker deals, pause lodgement until the triage is honest. Use app.fixmybadcredit.com.au for a free file analysis once you have the PDFs.
What “good enough” looks like before you apply
You do not need a perfect file. You need an honest map of what lenders will see on Equifax and Experian, a plan for anything non-compliant or incorrect, and enough discipline to stop adding hard enquiries while that plan runs. Brokers would rather wait two weeks for a clean story than inherit four declines.
If a listing is lawful and must age, say so early. If it is challengeable, gather notices and chronologies before you phone the creditor angry. Measured files get better outcomes than chaotic ones.
Internal links worth keeping open: free credit reports, default removal guide, and the credit repair lawyers Australia cornerstone.
Free reports are the starting line
Under Australian credit reporting rules, a credit reporting body must give you a free consumer credit report once every three months (OAIC). You can also seek free access after a credit refusal within the past 90 days, or after a correction. Get Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, treat illion as history, not a current third bureau you must pull separately.
Store PDFs somewhere durable. Portal links expire. Score dials without listings are not enough for a dispute or a broker pack.
Putting it into practice this month
Start with both free Equifax and Experian consumer credit reports. Under OAIC guidance you can access a free consumer credit report from each credit reporting body once every three months, and you should also ask about free access after a credit refusal or after a correction. Save the PDFs. Compare identity details, defaults, serious credit infringements, judgments, enquiries and repayment history information side by side.
Next, write a dated chronology for anything that looks wrong: notices received or not received, hardship emails, payments, address changes, and collector contact. Send a clear written dispute to the credit provider that disclosed the information, attach your evidence, and diary the response timeframes under the Privacy (Credit Reporting) Code. Use the bureau dispute process where required. If the firm is an AFCA member and internal dispute resolution fails, AFCA is free for eligible consumers. OAIC pathways may fit some credit reporting privacy complaints. The National Debt Helpline on 1800 007 007 remains available for budgeting and hardship conversations. Here is how our credit repair process works.
If a broker deadline is close, a judgment or clearout is involved, or the creditor contests the facts, get a legal triage rather than spraying new hard enquiries across lenders. Reach us through our contact form, call 1300 667 218, or book a 15-minute intro call. Read the full framework on our credit repair lawyers Australia cornerstone. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. Postal address: PO Box 169, Aspley QLD 4034.
FAQ
Is credit repair illegal in Australia?
No. Disputing inaccurate or non-compliant credit reporting information is a recognised consumer right. Misleading conduct and unlicensed legal practice are the problems ASIC targets.
Do I need a lawyer?
Not always. Simple identity errors can be DIY. Contested defaults, judgments, and deadline-driven broker deals often benefit from legal help.
What success rate should I trust?
One that defines the cohort, is independently audited, and is dated. Vague “most clients succeed” claims are marketing, not evidence.
General information only. Not legal advice for your circumstances. Liability limited by a scheme approved under Professional Standards Legislation.

Leave A Comment