
Updated 16 October 2026. By Graham Doessel.
Regulator action against credit repair businesses is a consumer education moment. Verify who you hire, avoid guaranteed outcomes, insist on written fees, and keep using free Equifax and Experian reports every three months plus AFCA/OAIC where they fit. Lawful correction of inaccurate or non-compliant credit reporting information remains legitimate.
Hi, I’m Graham. Headlines about shonks make good people freeze. Freezing is how Credit Prison stays locked. Read the lessons, then open your PDFs.
What enforcement cases usually allege
Pressure selling, misleading success claims, unclear fees, and poor handling of people already under stress. ASIC and MoneySmart material have warned about predatory credit repair for years. When proceedings start, look past the drama to the conduct pattern, then audit any operator you are considering against that pattern.
What it does not mean
It does not mean every credit repair pathway is illegal. Correcting credit reporting information that is inaccurate or non-compliant under the Privacy Act Part IIIA and the Privacy (Credit Reporting) Code is still a real legal pathway. A specialist credit repair lawyers Australia engagement is not the same as an unlicensed letter mill. ASIC has acted on this before; see the ASIC crackdown on payday lenders and credit repair agencies.
Consumer checklist after an enforcement headline
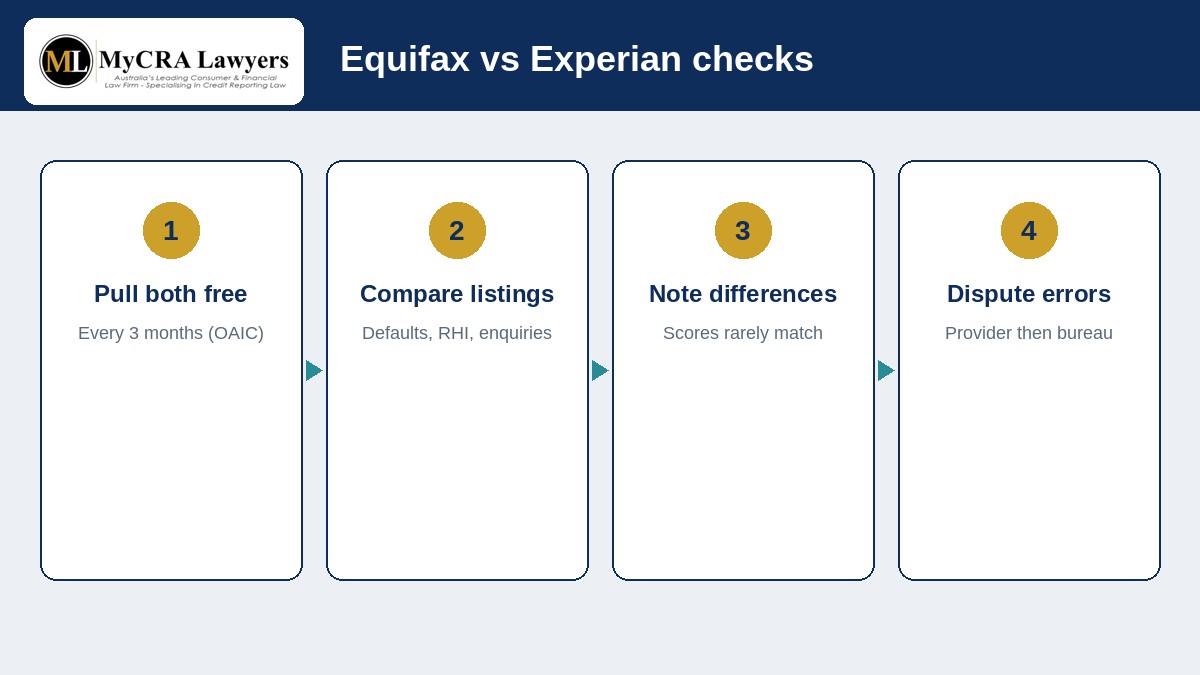
- Pull free Equifax and Experian reports (every three months).
- List every default, enquiry, judgment and RHI mark yourself.
- Ask any repair firm: law practice status, fixed fees in writing, independently audited success definition, both-bureau coverage.
- Use free rails: AFCA (eligible firms), OAIC (privacy), National Debt Helpline 1800 007 007.
- Start with a free analysis at app.fixmybadcredit.com.au before signing anything.
How to stress-test a success rate
Ask what was counted, what was excluded, who audited it, and what period it covers. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees quoted before you start. Selected matters include a Money Back Guarantee on the published terms. If an operator refuses to define the rate, treat the percentage as advertising.
Bureau landscape reminder
Australia’s mainstream consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau; from 1 April 2026 an Experian report includes data previously held separately by illion. You do not need a separate illion report for a current cleanup. Free consumer reports are available every three months (OAIC), with additional free access after a credit refusal within 90 days or after a correction.
A practical week-one plan
Day 1: request free Equifax and Experian reports. Day 2: save the PDFs and build a one-page negatives list (defaults, enquiries, judgments, RHI, identity errors). Day 3: freeze non-essential credit applications. Day 4: send obvious correction requests with evidence. Day 5: upload the messiest file to app.fixmybadcredit.com.au for a free credit file analysis, or book a 15-minute intro call if a lending deadline is close.
That sequence beats a month of scrolling ads and creates a paper trail AFCA, OAIC and a specialist firm can use.
When to call us
If DIY stalls, the creditor contests notices, or a home loan is on a clock, get a specialist read. We will tell you if prospects look low. Before you pay anyone, run through these questions to ask before hiring a credit repairer.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
Evidence that actually moves the needle
Keep a single folder for each listing: the bureau PDF page, statements, notices (or proof you never received them), hardship emails, change-of-address records, and a one-page timeline. Creditors and AFCA respond to chronology. A three-page emotional essay without dates usually dies in an inbox.
After any settlement or correction promise, re-pull Equifax and Experian. Do not trust a phone assurance that “it will fall off.” Confirm the text on the file lenders will read. Then wait a beat before new applications so you are not testing the file with a fresh hard enquiry on the same afternoon a correction posts.
Mistakes that keep people stuck
- Applying at more lenders to “see who says yes” while a contested default is still live
- Paying every listing first without checking notices and compliance
- Checking only one bureau or only a score app
- Hiring the loudest advertiser without verifying law-practice status and fee terms
- Waiting until exchange of contracts to open the PDF
Avoid those five and you are already ahead of most people who call us in a panic. Free reports every three months, both current bureaus, written disputes, and an honest specialist when DIY stalls, that is the whole playbook.
How this connects to a home loan or refinance
Most people only care about credit repair when a broker deadline appears. That is fine, just do not let the deadline force blind lodging. Show your broker both Equifax and Experian PDFs. Ask which lenders on their panel will even look at your negatives. Pause car yards, BNPL and “rate check” tools that leave hard footprints. If a listing looks non-compliant, get it audited before the next application, not after the third decline.
If settlement is close and the file is contested, say so early on the intro call. Urgency changes prioritisation; it does not create magical guarantees. Fixed fees are still quoted in writing. Free analysis remains available at app.fixmybadcredit.com.au when you already have PDFs, or when you need help obtaining them.
Remember: free consumer credit reports every three months are a right under Australian credit reporting rules (OAIC). Use that right before you spend money or burn enquiry capacity.
Putting it into practice this month
Start with both free Equifax and Experian consumer credit reports. Under OAIC guidance you can access a free consumer credit report from each credit reporting body once every three months, and you should also ask about free access after a credit refusal or after a correction. Save the PDFs. Compare identity details, defaults, serious credit infringements, judgments, enquiries and repayment history information side by side.
Next, write a dated chronology for anything that looks wrong: notices received or not received, hardship emails, payments, address changes, and collector contact. Send a clear written dispute to the credit provider that disclosed the information, attach your evidence, and diary the response timeframes under the Privacy (Credit Reporting) Code. Use the bureau dispute process where required. If the firm is an AFCA member and internal dispute resolution fails, AFCA is free for eligible consumers. OAIC pathways may fit some credit reporting privacy complaints. The National Debt Helpline on 1800 007 007 remains available for budgeting and hardship conversations. Our credit repair process is set out in plain English.
If a broker deadline is close, a judgment or clearout is involved, or the creditor contests the facts, get a legal triage rather than spraying new hard enquiries across lenders. Email docs@mycralawyers.com.au, call 1300 667 218, or book a 15-minute intro call. Read the full framework on our credit repair lawyers Australia cornerstone. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. Selected matters include a Money Back Guarantee on published terms. Postal address: PO Box 169, Aspley QLD 4034.
FAQ
Did ASIC ban credit repair?
No. Enforcement targets harmful conduct. Lawful correction work remains available.
How do I verify a law firm?
Ask for the practice name and how to check the relevant law society register.
Should I stop a legitimate dispute because of headlines?
Not automatically. Keep using free reports and evidence-based correction pathways.
How often are free reports available?
Once every three months per credit reporting body (OAIC), plus specified extras.
Where do I start with MyCRA?
Free analysis at app.fixmybadcredit.com.au or a 15-minute intro call on 1300 667 218.
This is general information, not legal advice. Liability limited by a scheme approved under Professional Standards Legislation.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | PO Box 169, Aspley QLD 4034

Leave A Comment