
Names and identifying details in this case study have been changed to protect our client’s privacy.
Alana found out about her default the most awkward way possible. Her salary packaging provider ran a check, and there it was: a default from her bank, now owned by a debt buyer. She was about to apply for a car lease. She had no idea the debt had even gone overdue.
The amount was small, a little under $900. The damage wasn’t. A default sits on your credit file for five years, and plenty of lenders won’t look past one, whatever the size.
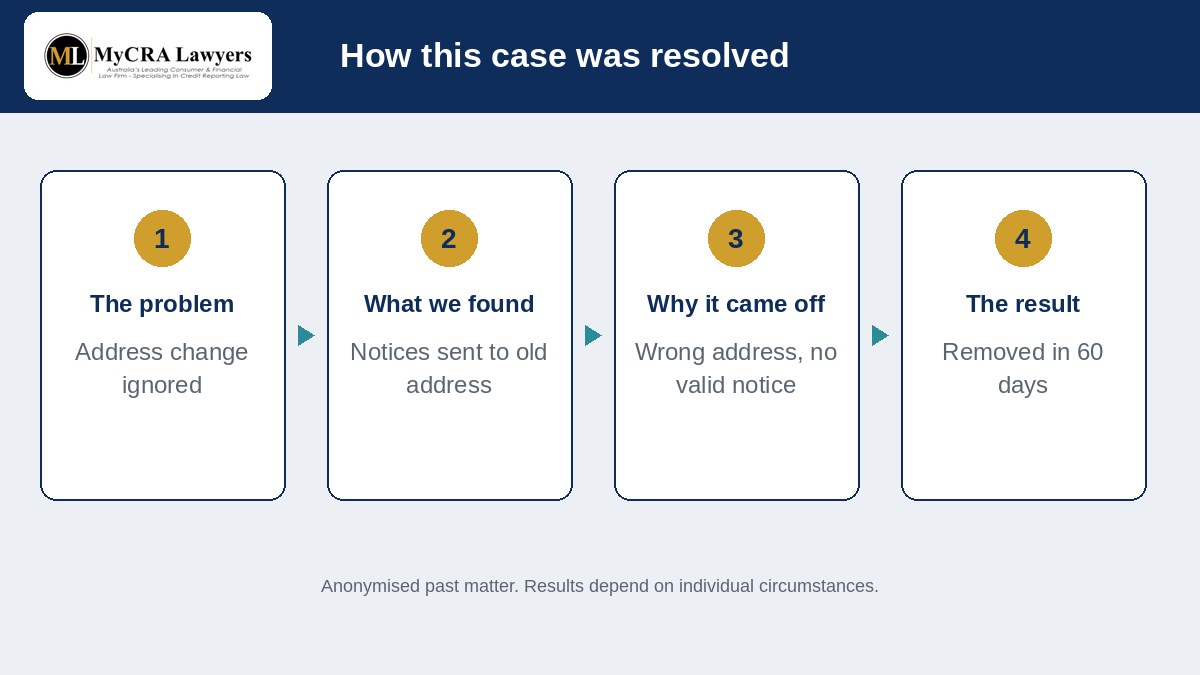
How a small debt became a default
Alana had told her bank she’d moved. The bank never updated its records. So the overdue notices, and the formal default notice, went to an address she no longer lived at. The bank also had her mobile and work numbers on file. Nobody called.
By the time the account was sold to a debt buyer, the default was already on her file. Alana did what most people do when they finally find out. She rang the collector and set up a payment plan. Paying a debt doesn’t remove the default, though. It just changes the status to “paid”.
What we found
Alana’s mortgage broker referred her to us. When we asked the debt buyer for the file, its first answer was a flat no. It said the listing complied with the Credit Reporting Code.
We didn’t accept that. A creditor has to send its default notices to your last known address. If you’ve told them you moved and they keep writing to the old place, they haven’t met that requirement. Alana’s bank had the right contact details. It just didn’t use them.
Why it came off
We put the incorrect address argument to the debt buyer in writing, along with a settlement offer based on part payment of the balance. Faced with a listing that rested on notices sent to the wrong place, they agreed to remove it.
The result
We started work on 20 November. The default came off on 19 January, 60 days later. Alana went back to her lease application with a clean file and her broker could get on with the job.
What this means for you
If you’ve moved house and a default turned up later, check where the notices were sent. “We sent it” isn’t the same as “we sent it to the right place”. Our credit repair lawyers look at exactly this kind of detail, because it’s often where a creditor’s case falls over.
This is a past matter. Names and identifying details have been changed to protect our client’s privacy.
Results depend on individual circumstances. Every credit file is different, and a past result doesn’t guarantee the outcome of your matter. This case study is general information, not legal advice.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | Book a 15-minute intro call

Leave A Comment