
Updated 16 October 2026. By Graham Doessel.
The best broker referrals happen before a deal dies on the panel. Referring early protects the client and the broker’s panel reputation. Prefer independently audited results, fixed fees in writing, both-bureau coverage, and firms that will decline hopeless matters.
Hi, I’m Graham. The best broker referrals are not “fix my mate’s score.” They are “this default looks off, can you audit it before we lodge?” That is how you keep clients out of Credit Prison and keep your own lodgement stats honest.
1. Fewer surprise declines
Auto-declines waste valuation fees, spoil vendor relationships and burn enquiry capacity. A pre-lodge file read on Equifax and Experian catches landmines early. Surprises belong in birthday parties, not credit policy.
2. Cleaner enquiry management
Clients often create the damage between broker appointments. A referred legal audit pairs with a hard rule: no new applications until strategy is clear. See enquiry removal.
3. Legal pathways beyond template letters
Non-law letter mills hit a wall when creditors contest notices or hardship facts. A law practice can advise and act inside the Privacy Act / Credit Reporting Code framework. Cornerstone: credit repair lawyers Australia.
4. Independently audited outcomes
On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees quoted before you start. Selected matters include a Money Back Guarantee on the published terms. Brokers should ask any repair operator for the audit definition, what was counted, what was excluded. Marketing percentages without a certificate are just advertising.
5. Fixed fees and clear terms
Get fees in writing before work starts. Ask about extras and whether a Money Back Guarantee applies on published terms. Pricing overview: how much is.
6. Both-bureau coverage
Equifax and Experian only as current mainstream consumer CRBs. Former illion data sits with Experian from 1 April 2026. Free client reports every three months (OAIC). If a repair outfit shrugs at the second bureau, keep walking. Before you pay anyone, run through these questions to ask before hiring a credit repairer.
7. An honest no
If chances are low, we say so on the intro call. That protects your client from paying for theatre and protects your referral brand. A “no” today can still leave the client with a DIY map via the free analysis tool.
Client self-serve start: app.fixmybadcredit.com.au. Call 1300 667 218 or email docs@mycralawyers.com.au.
How to brief MyCRA quickly
Send both bureau PDFs, the deal timeline, and what the lender declined on if known. That beats a vague “credit is a bit messy” email every time.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
Referral timing mistakes
The expensive mistake is referring after the client has already collected declines. Each decline can add another hard enquiry and shrink the lender list further. The cheap mistake is never referring and hoping a non-conforming lender will ignore a defective default. Both mistakes are avoidable with a pre-lodge triage habit.
Build a simple rule: if there is a default, judgment, SCI, or messy enquiry cluster, pause and assess before the first full panel shot. Soft enquiries and free reports do not replace that pause, they enable it.
What good looks like after referral
You get a clear prospects conversation, a fee quote in writing, and a plan that either proceeds or hands the client a DIY map. You keep the broker relationship warm either way. That is the standard we aim for on intro calls and via the free analysis tool. Brokers see this often, as in an Australian broker’s account of unlawful credit reporting.
Partnering without blurry lines
Keep referral arrangements transparent and compliant with your own licensee rules. Do not invent success guarantees on our behalf. Send facts, get a written scope, and let the legal engagement sit between MyCRA and the client. Clean partnerships last.
Seven referral triggers brokers use
- Live consumer default inside five years
- Judgment still showing
- Serious credit infringement / clearout
- Enquiry cluster from payday/BNPL/car yards
- Identity or address mash-up
- Hardship-era listing with a messy email trail
- Client already burned by an unlicensed “repair” outfit
Refer with both PDFs and a goal date. We triage; you keep the relationship.
Broker referral guide · cornerstone.
Equifax and Experian: always both
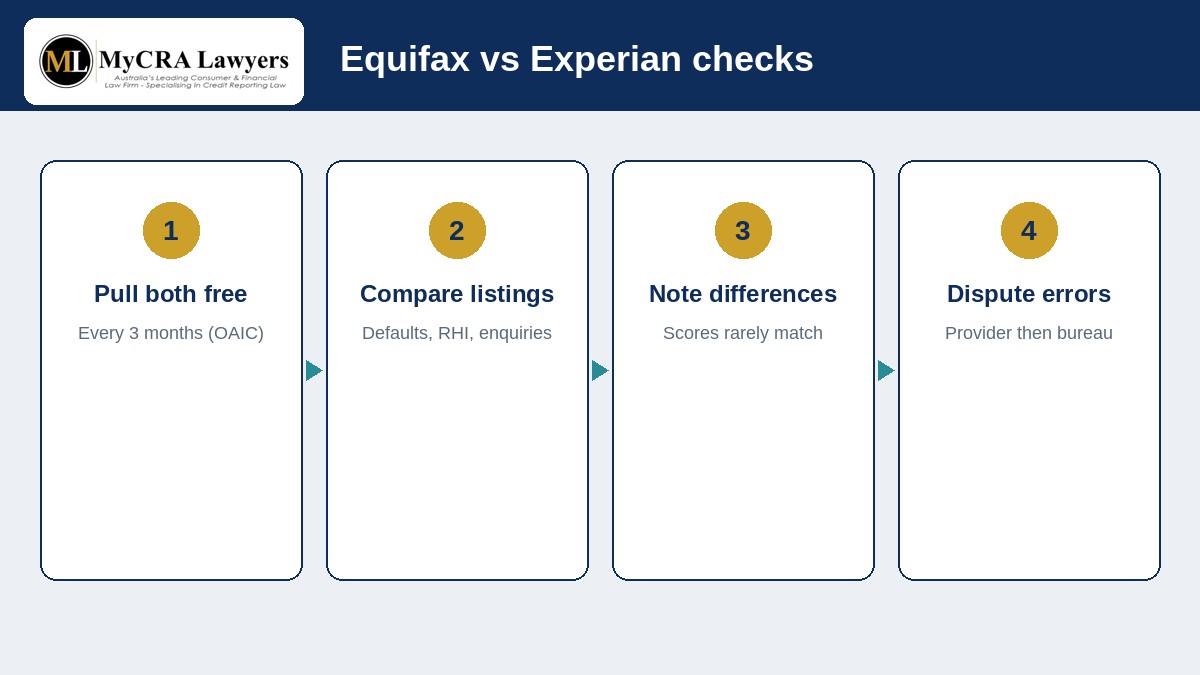
Australia’s consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, so you do not need a separate illion report today. Scores rarely match. Free consumer reports are available every three months (OAIC). After a refusal, ask about free access tied to that decision. Save PDFs, not only score dials.
A simple cleanup order
- Identity and contact data
- Defaults and serious credit infringements
- Judgments
- Enquiries
- Repayment history information
- Hardship flags
Dispute clear errors before you generate new hard enquiries. For broker deals, pause lodgement until the triage is honest. Use app.fixmybadcredit.com.au for a free file analysis once you have the PDFs.
Free reports are the starting line
Under Australian credit reporting rules, a credit reporting body must give you a free consumer credit report once every three months (OAIC). You can also seek free access after a credit refusal within the past 90 days, or after a correction. Get Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, treat illion as history, not a current third bureau you must pull separately.
Store PDFs somewhere durable. Portal links expire. Score dials without listings are not enough for a dispute or a broker pack.
Putting it into practice this month
Start with both free Equifax and Experian consumer credit reports. Under OAIC guidance you can access a free consumer credit report from each credit reporting body once every three months, and you should also ask about free access after a credit refusal or after a correction. Save the PDFs. Compare identity details, defaults, serious credit infringements, judgments, enquiries and repayment history information side by side.
Next, write a dated chronology for anything that looks wrong: notices received or not received, hardship emails, payments, address changes, and collector contact. Send a clear written dispute to the credit provider that disclosed the information, attach your evidence, and diary the response timeframes under the Privacy (Credit Reporting) Code. Use the bureau dispute process where required. If the firm is an AFCA member and internal dispute resolution fails, AFCA is free for eligible consumers. OAIC pathways may fit some credit reporting privacy complaints. The National Debt Helpline on 1800 007 007 remains available for budgeting and hardship conversations. Our credit repair process is set out in plain English.
If a broker deadline is close, a judgment or clearout is involved, or the creditor contests the facts, get a legal triage rather than spraying new hard enquiries across lenders. Email docs@mycralawyers.com.au, call 1300 667 218, or book a 15-minute intro call. Read the full framework on our credit repair lawyers Australia cornerstone. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. Selected matters include a Money Back Guarantee on published terms. Postal address: PO Box 169, Aspley QLD 4034.
FAQ
When should a broker refer?
Before lodging, when negatives look contested or non-compliant.
Is MyCRA only for consumers?
We work Australia-wide with consumers and broker-referred clients.
Do you guarantee removal?
No law firm can promise a removal. Selected consumer default work carries a Money Back Guarantee, which refunds the professional fees for a listing that isn’t removed; it is not a promise of the result. We quote our independently audited success rate with its qualifiers.
How do clients get free reports?
Every three months from Equifax and Experian (OAIC).
Contact?
1300 667 218 · docs@mycralawyers.com.au
This is general information, not legal advice. Liability limited by a scheme approved under Professional Standards Legislation.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | PO Box 169, Aspley QLD 4034

Leave A Comment