
Updated 31 October 2026. By Graham Doessel.
A better rate means nothing if the file triggers an auto-decline. Use this checklist in the fortnight before you authorise a full mortgage application. It is written for borrowers and for brokers who are tired of cleaning up avoidable wreckage.
The checklist
- Pull Equifax and Experian: free consumer reports every three months (OAIC). Save PDFs.
- Identity block: names, DOB, licence, addresses. Fix mismatches first.
- Defaults: list date, amount, paid status, creditor. Audit notices.
- Judgments: different pathway from defaults.
- Enquiries: count the last 12–24 months; pause new ones.
- RHI: late marks on revolving and mortgage-like accounts.
- BNPL / payday residue: disclose to the broker.
- Hardship flags: bring the emails.
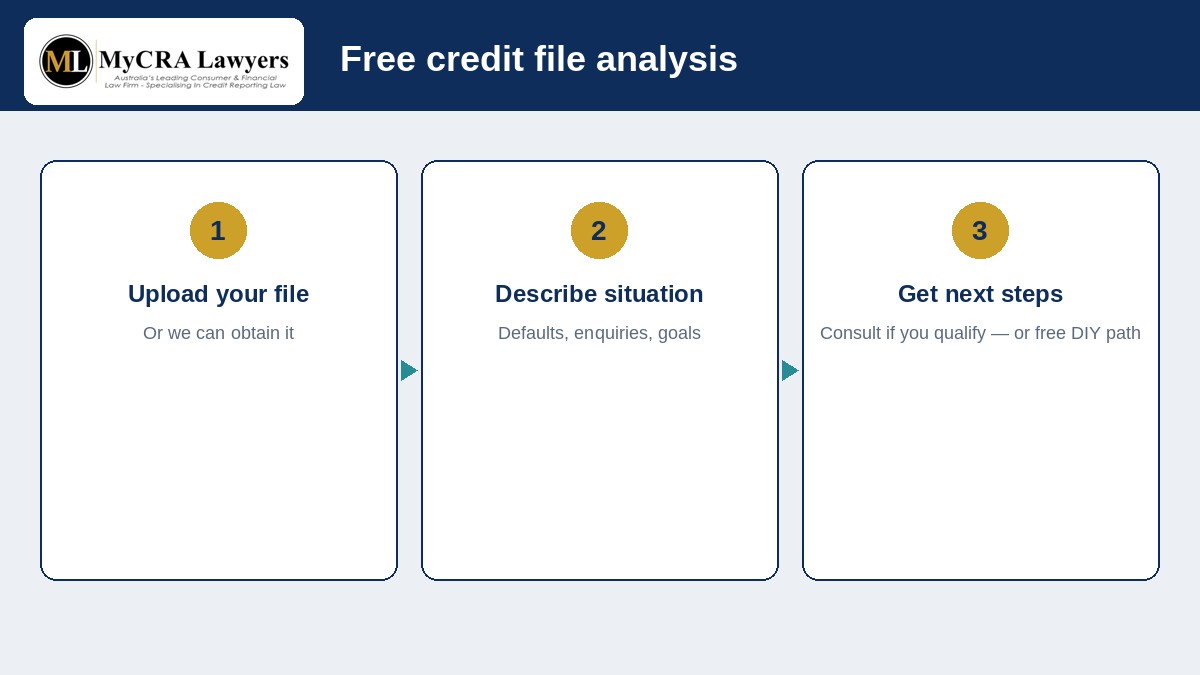
- Run a free analysis: app.fixmybadcredit.com.au.
- Only then lodge: or pause for repair.
Guides: free credit report, check before you refinance, cornerstone.
If something fails the checklist
Do not “test” three lenders to see what happens. That is how enquiry clusters are born. Fix or contextualise first. We explain the scoring side in how credit enquiries affect your credit score.
Our contact form · 1300 667 218 · intro call. PO Box 169, Aspley QLD 4034.
Broker-ready pack
When the checklist is clean, hand the broker:
- Both PDF reports dated within the last few weeks
- A one-page explanation of any remaining marks
- Evidence for anything already corrected
- A list of every credit application in the last two years you remember
Brokers are not psychic. Surprises at credit assessment cost everyone. Brokers can limit the damage; see how brokers protect the client file from enquiry spikes.
If you find a problem mid-checklist
Stop. Do not lodge “to see what happens.” Use the free analysis tool, then decide DIY dispute vs legal help. Our broker pause guide is the companion to this checklist.
On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees. Money Back Guarantee: we run this offer from time to time for certain creditors, so ask us if one is running.
Broker-ready pack after the checklist
Hand over both recent PDFs, a one-page explanation of remaining marks, evidence of corrections already made, and a list of recent applications. If anything fails the checklist, stop lodging and triage, DIY, AFCA, or legal help.
Equifax and Experian: always both
Australia’s consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, so you do not need a separate illion report today. Scores rarely match. Free consumer reports are available every three months (OAIC). After a refusal, ask about free access tied to that decision. Save PDFs, not only score dials.
A simple cleanup order
- Identity and contact data
- Defaults and serious credit infringements
- Judgments
- Enquiries
- Repayment history information
- Hardship flags
Dispute clear errors before you generate new hard enquiries. For broker deals, pause lodgement until the triage is honest. Use app.fixmybadcredit.com.au for a free file analysis once you have the PDFs.
What “good enough” looks like before you apply
You do not need a perfect file. You need an honest map of what lenders will see on Equifax and Experian, a plan for anything non-compliant or incorrect, and enough discipline to stop adding hard enquiries while that plan runs. Brokers would rather wait two weeks for a clean story than inherit four declines.
If a listing is lawful and must age, say so early. If it is challengeable, gather notices and chronologies before you phone the creditor angry. Measured files get better outcomes than chaotic ones.
Internal links worth keeping open: free credit reports, default removal guide, and the credit repair lawyers Australia cornerstone.
Free reports are the starting line
Under Australian credit reporting rules, a credit reporting body must give you a free consumer credit report once every three months (OAIC). You can also seek free access after a credit refusal within the past 90 days, or after a correction. Get Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, treat illion as history, not a current third bureau you must pull separately.
Store PDFs somewhere durable. Portal links expire. Score dials without listings are not enough for a dispute or a broker pack.
Common mistakes that keep people in Credit Prison
- Applying again the morning after a decline
- Paying a default because a collector said it would “come off”
- Hiring the loudest repair advert without checking fees or practising status
- Disputing by phone only and keeping no chronology
- Checking one bureau and assuming the other matches
- Ignoring RHI grids because there is no default yet
Most of those mistakes are fixable with process. Start with both free reports, then pick DIY, AFCA/OAIC, or a law firm based on evidence and deadlines, not panic.
How MyCRA usually scopes a file
We ask for both bureau PDFs and a short goal (refinance date, auction, car loan, cleanup). We say if chances look poor. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running.
Reach us through our contact form, call 1300 667 218 or 07 3124 7133, book a 15-minute intro call, or write to PO Box 169, Aspley QLD 4034. Full framework: credit repair lawyers Australia.
AFCA, OAIC and patience
IDR with the credit provider comes first for most listing disputes. AFCA is free for eligible consumers complaining about members. OAIC pathways matter for some credit reporting privacy issues. Timelines stretch into weeks or months when facts are contested. If a broker has a hard settlement date, say so early and plan parallel options, including waiting out a compliant listing when that is the honest answer.
National Debt Helpline 1800 007 007 remains the free budgeting and hardship sounding board outside a law firm.
Putting it into practice this month
Start with both free Equifax and Experian consumer credit reports. Under OAIC guidance you can access a free consumer credit report from each credit reporting body once every three months, and you should also ask about free access after a credit refusal or after a correction. Save the PDFs. Compare identity details, defaults, serious credit infringements, judgments, enquiries and repayment history information side by side.
Next, write a dated chronology for anything that looks wrong: notices received or not received, hardship emails, payments, address changes, and collector contact. Send a clear written dispute to the credit provider that disclosed the information, attach your evidence, and diary the response timeframes under the Privacy (Credit Reporting) Code. Use the bureau dispute process where required. If the firm is an AFCA member and internal dispute resolution fails, AFCA is free for eligible consumers. OAIC pathways may fit some credit reporting privacy complaints. The National Debt Helpline on 1800 007 007 remains available for budgeting and hardship conversations. Here is how our credit repair process works.
If a broker deadline is close, a judgment or clearout is involved, or the creditor contests the facts, get a legal triage rather than spraying new hard enquiries across lenders. Reach us through our contact form, call 1300 667 218, or book a 15-minute intro call. Read the full framework on our credit repair lawyers Australia cornerstone. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. Postal address: PO Box 169, Aspley QLD 4034.
FAQ
How far in advance should I check?
At least two weeks before lodging; longer if you already know about a default or judgment.
Is one bureau enough?
No. Lenders use Equifax, Experian, or both. Scores will not match.
General information only. Not legal advice for your circumstances. Liability limited by a scheme approved under Professional Standards Legislation.

Leave A Comment