
Names and identifying details in this case study have been changed to protect our client’s privacy.
Hannah did a favour for her sister, and it nearly cost her a home.
When they were living together, Hannah bought a car for her sister and put the loan in her own name with a big bank’s car finance arm. Her sister agreed to make the repayments. Later, her sister told her the car was all paid off.
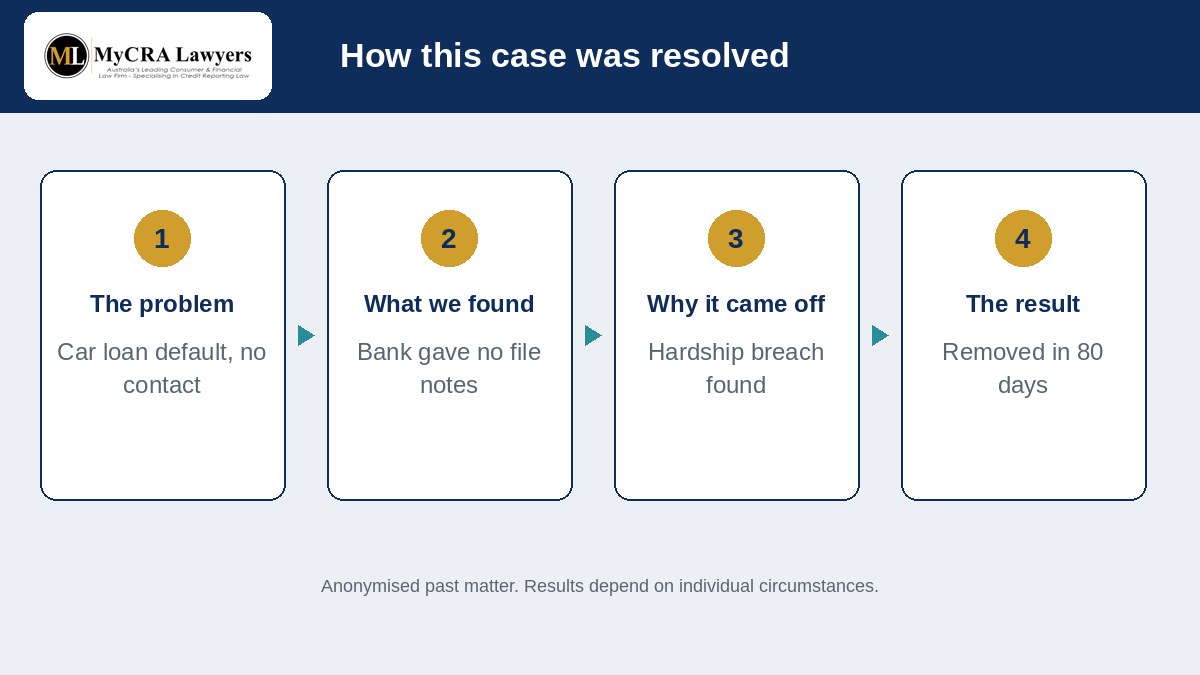
It wasn’t. Hannah only learned that when she applied for a home loan and was declined. There was a default on her file for about $2,300.
Nobody told Hannah
Hannah never received a single letter about the arrears. The lender had her mobile number, but no one called her about missed payments either. As soon as she found out, she paid the loan out in full. The default stayed.
What we found
We asked the bank for its file notes and correspondence. It didn’t provide them. To us, that suggested the bank hadn’t properly investigated Hannah’s complaint at all.
So we took it further. We prepared a complaint to the financial ombudsman, setting out what had happened and what the bank had failed to do.
Why it came off
The ombudsman found the bank had breached its hardship obligations. The bank didn’t dispute the preliminary findings. The ombudsman ordered the default removed, and ordered the bank to pay Hannah $500 in compensation.
That’s worth pausing on. Hannah didn’t only get her file fixed. She was compensated for the bank’s failures.
The result
The default came off 80 days after we started. Hannah could go back to her home loan application with a clean file.
What this means for you
A lot of people assume that because the debt was technically in their name, they have no case. Not always. If the lender didn’t contact you, didn’t consider hardship, or can’t produce its own records, those are real grounds. Our credit repair lawyers know when a matter is worth taking to the ombudsman, and when it isn’t.
This is a past matter. Names and identifying details have been changed to protect our client’s privacy.
Results depend on individual circumstances. Every credit file is different, and a past result doesn’t guarantee the outcome of your matter. This case study is general information, not legal advice.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | Book a 15-minute intro call

Leave A Comment