
Updated 19 October 2026. By Graham Doessel.
A practical cleanup checklist beats generic “credit tips” content. Use a practical 2026 sequence instead: see both bureau files, stop enquiry bleeding, dispute only what the rules support, use free escalation rails, then hire a specialist when contested.
Hi, I’m Graham. Tips do not get you out of Credit Prison. Habits do. Start with the PDFs.
Why this matters now
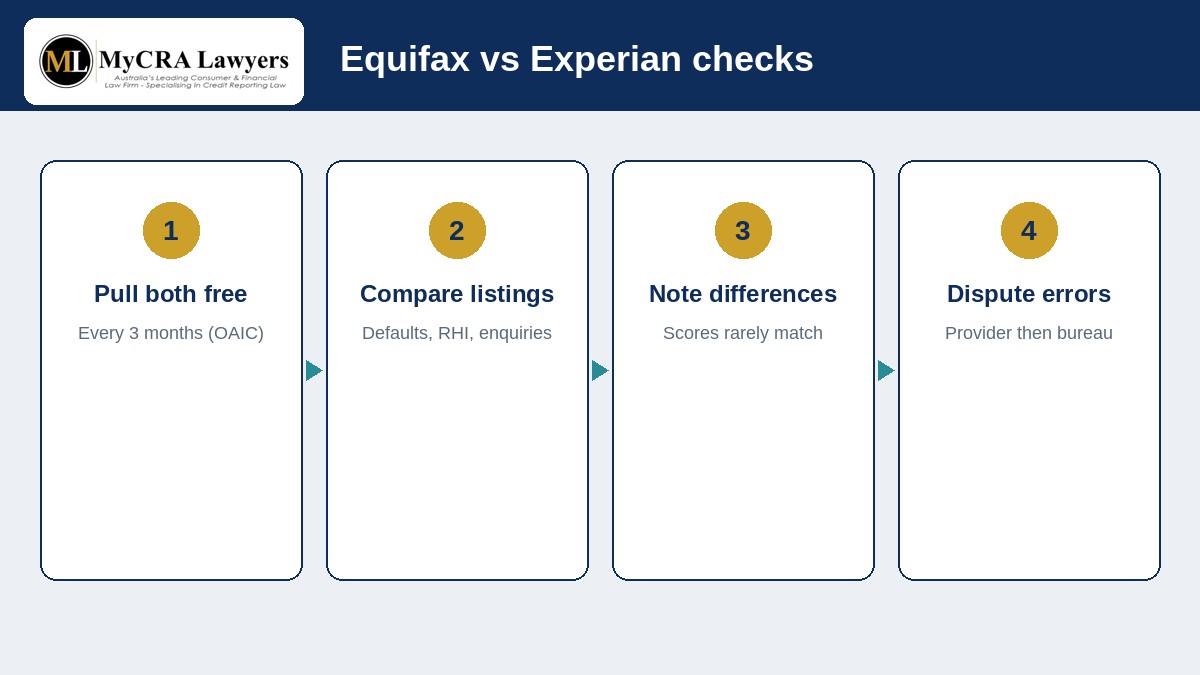
Pull Equifax and Experian every three months. Save full PDFs. Freeze non-essential applications. Build a negatives table. Write to providers with evidence. Diary Code timeframes. Use AFCA/OAIC/Debt Helpline where they fit.
What to do in practice
Try a free analysis at app.fixmybadcredit.com.au. Interview any paid operator using our hiring questions.
Bureau and free-access reminder
Australia’s mainstream consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau; from 1 April 2026 an Experian report includes data previously held separately by illion. You do not need a separate illion report for a current cleanup. Free consumer reports are available every three months (OAIC), with additional free access after a credit refusal within 90 days or after a correction.
Detail that usually gets missed
Use a specialist via credit repair lawyers Australia when DIY stalls. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees quoted before you start. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running.
A practical week-one plan
Day 1: request free Equifax and Experian reports. Day 2: save the PDFs and build a one-page negatives list (defaults, enquiries, judgments, RHI, identity errors). Day 3: freeze non-essential credit applications. Day 4: send obvious correction requests with evidence. Day 5: upload the messiest file to app.fixmybadcredit.com.au for a free credit file analysis, or book a 15-minute intro call if a lending deadline is close.
That sequence beats a month of scrolling ads and creates a paper trail AFCA, OAIC and a specialist firm can use.
When MyCRA gets involved
On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees quoted before you start. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. You can see how we repair credit, step by step.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
A realistic scenario
Imagine a broker calls on a Thursday afternoon with a decline. The income stacked. The LVR looked fine. Then the credit policy engine tripped on something that had been sitting on the file for years, or on a cluster of hard enquiries from a chaotic quarter. The expensive response is to lodge again immediately and hope. The adult response is to pull both free bureau reports, map the negatives, freeze new applications, and decide what is actually challengeable under the Privacy Act and Credit Reporting Code before the next enquiry lands.
That is the difference between collecting declines and running a cleanup. It is also why our credit repair lawyers Australia cornerstone keeps pointing back to evidence, notices and process rather than score theatre.
If you already have the PDFs, email docs@mycralawyers.com.au or use app.fixmybadcredit.com.au. If you do not, get the free reports first, every three months is a right, not a favour. Start with how to get your free credit report if you don’t have both PDFs yet.
Evidence that actually moves the needle
Keep a single folder for each listing: the bureau PDF page, statements, notices (or proof you never received them), hardship emails, change-of-address records, and a one-page timeline. Creditors and AFCA respond to chronology. A three-page emotional essay without dates usually dies in an inbox.
After any settlement or correction promise, re-pull Equifax and Experian. Do not trust a phone assurance that “it will fall off.” Confirm the text on the file lenders will read. Then wait a beat before new applications so you are not testing the file with a fresh hard enquiry on the same afternoon a correction posts.
Mistakes that keep people stuck
- Applying at more lenders to “see who says yes” while a contested default is still live
- Paying every listing first without checking notices and compliance
- Checking only one bureau or only a score app
- Hiring the loudest advertiser without verifying law-practice status and fee terms
- Waiting until exchange of contracts to open the PDF
Avoid those five and you are already ahead of most people who call us in a panic. Free reports every three months, both current bureaus, written disputes, and an honest specialist when DIY stalls, that is the whole playbook.
How this connects to a home loan or refinance
Most people only care about credit repair when a broker deadline appears. That is fine, just do not let the deadline force blind lodging. Show your broker both Equifax and Experian PDFs. Ask which lenders on their panel will even look at your negatives. Pause car yards, BNPL and “rate check” tools that leave hard footprints. If a listing looks non-compliant, get it audited before the next application, not after the third decline. ASIC has acted on this before; see the ASIC crackdown on payday lenders and credit repair agencies.
If settlement is close and the file is contested, say so early on the intro call. Urgency changes prioritisation; it does not create magical guarantees. Fixed fees are still quoted in writing. Free analysis remains available at app.fixmybadcredit.com.au when you already have PDFs, or when you need help obtaining them.
Remember: free consumer credit reports every three months are a right under Australian credit reporting rules (OAIC). Use that right before you spend money or burn enquiry capacity.
FAQ
Where do I start?
Free Equifax and Experian reports every three months, then a free analysis or intro call.
Do I need both bureaus?
Yes, Equifax and Experian.
Will checking my own file create a hard enquiry?
Accessing your own free credit reporting information should not create a hard lender enquiry.
Can outcomes be guaranteed?
No. No law firm can promise a removal. From time to time we run a Money Back Guarantee offer on listings with certain creditors. When it applies, it refunds your professional fees for a listing that is not removed. It is not a promise of the result. Which creditors it covers changes, so ask us if one is running. We quote our independently audited success rate with its qualifiers and will say if prospects look low.
How do I contact MyCRA?
1300 667 218 · docs@mycralawyers.com.au · PO Box 169, Aspley QLD 4034
This is general information, not legal advice. Liability limited by a scheme approved under Professional Standards Legislation.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | PO Box 169, Aspley QLD 4034

Leave A Comment