
Updated 22 November 2026. By Graham Doessel.
Short answer
Receiving Centrelink or other income support does not stop you checking your credit file, disputing wrong listings, asking for hardship, or getting legal help with consumer credit reporting problems. Lenders still assess serviceability, and some products will be harder to obtain on a low income, that is lending policy, not a ban on credit repair. Australians can get a free Equifax and Experian report every three months regardless of benefit status. For budget pressure, start with the National Debt Helpline on 1800 007 007 before you take on more credit.
Hi, I’m Graham. We hear the myths every week. “You’re on Centrelink, so nothing can come off your file.” “Banks freeze disputes if you get JobSeeker.” “Hardship is only for people with jobs.” None of that is how the Privacy Act or the credit reporting rules work. Income support can change what new credit you can service. It does not cancel your right to a correct file.
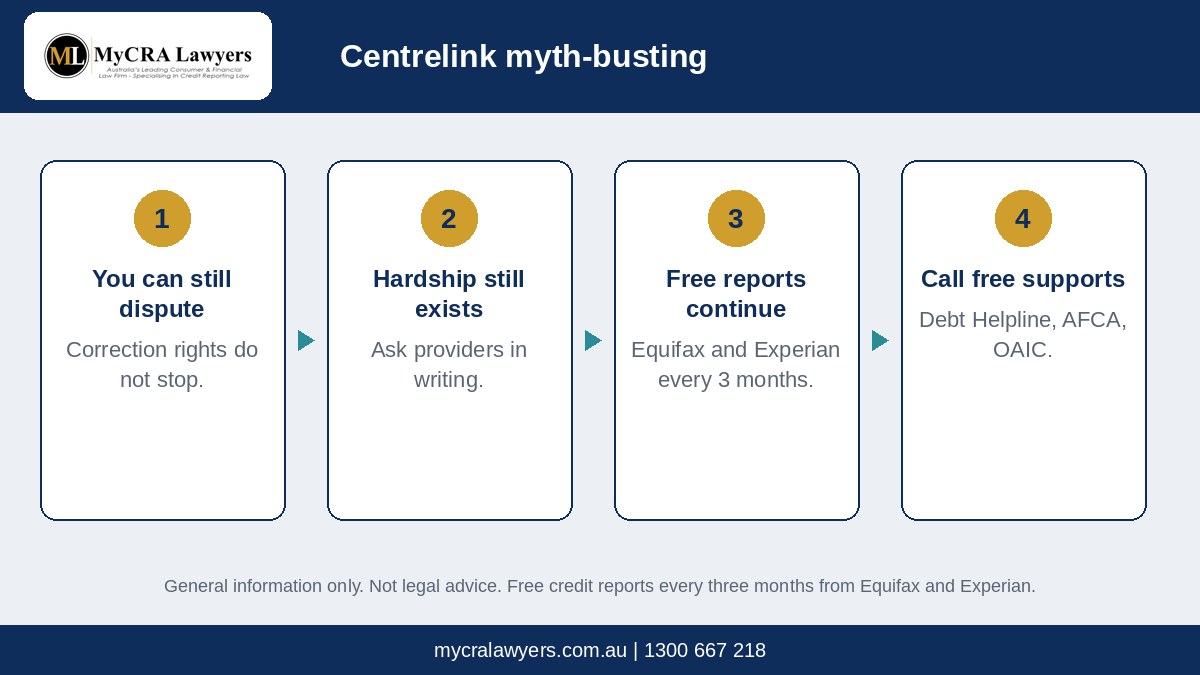
This guide knocks over the common myths and points you to the real pathways. It pairs with broader credit repair myths and financial hardship information on your credit file.
Myth 1: “Centrelink customers cannot dispute credit listings”
False. Correction rights under the Privacy Act and the CR Code do not depend on your employment status. If a default, enquiry or repayment mark is wrong, you can ask the credit provider and the bureau to correct it whether your income is wages, a pension, a benefit, or a mix.
What you need is the same as anyone else: both bureau reports, the timeline, and the documents that show the error.
Myth 2: “Being on income support stops hardship help”
False. Licensed credit providers must consider financial hardship requests for consumer credit. Job loss, illness and reduced hours are classic reasons people ask. Receiving Centrelink can be evidence that income has dropped, not a reason to refuse to read the request.
Ask in writing, keep the reply, and remember that while a hardship request is being assessed a default generally cannot be listed (with a limited exception for repeat same-basis requests). Details are in defaults during hardship.
Myth 3: “You cannot get free credit reports on benefits”
False. Australians can get a free consumer credit report from Equifax and from Experian every three months. Benefit status does not remove that right. Illion’s consumer bureau has been absorbed into Experian, so those two reports are the ones to order. Save the PDFs rather than relying on a score app alone, see credit score vs credit file.
Myth 4: “Lenders ignore your file if you receive Centrelink”
Mostly false, and dangerously misleading. Lenders still read defaults, enquiries and repayment history. Separately, they assess whether you can service a new loan. Income support may limit product options or loan size. That is a serviceability question. It is not permission for a creditor to leave an inaccurate five-year default untouched.
If a loan is declined, ask why in writing and check the file before you assume the benefit was the only reason, after a credit refusal.
Myth 5: “Credit repair is only for people who can pay big fees upfront”
Be careful with anyone who demands large money upfront for vague promises. MyCRA Lawyers quotes fixed fees in writing after we assess the file. From time to time we also run a Money Back Guarantee offer on listings with certain creditors, so ask us if one is running. We will also tell you when a listing looks like a wait-out rather than a viable dispute.
Free and low-cost help still comes first for many people:
- National Debt Helpline, 1800 007 007: free financial counselling
- AFCA: free for eligible consumers complaining about member firms
- OAIC: some credit reporting privacy complaints
- Community legal centres: for broader debt and consumer issues
What should you actually do if you are on income support and worried about your file?
- Order both free Equifax and Experian reports and mark anything you do not recognise.
- List your debts and due dates. Call the National Debt Helpline if the budget does not close.
- Ask each credit provider for hardship help in writing where you cannot meet repayments.
- Dispute clear reporting errors with evidence, wrong amount, wrong person, bad notices, hardship timing.
- Pause new credit applications (including BNPL) until the file and budget are steadier. See BNPL defaults on your credit file.
A free credit file analysis at app.FixMyBadCredit.com.au can help you see whether the main problem is a listing, a cluster of enquiries, or simply serviceability for the loan you want.
What we will not tell you
We will not promise that every listing comes off, or that income support somehow guarantees a lending approval once a default is gone. Credit repair is about accuracy and process. Lending is about risk and repayment capacity. Keeping those ideas separate saves people from expensive myths.
Myth 6: “Government benefits appear as a black mark on Equifax or Experian”
Your consumer credit report is not a Centrelink statement. It records credit accounts, repayment history, enquiries and listings. Receiving income support does not itself create a default. What can hurt the file are the same things that hurt anyone else: unpaid consumer credit, missed notices, and bursts of applications when money is tight.
If a listing appeared around the time your income changed, look at the creditor’s notices and hardship timeline – not at the benefit itself. Correct the reporting errors. Use hardship and counselling for the budget. Keep those jobs separate and both get easier.
How can MyCRA Lawyers help?
If you are on income support and a listing on your Equifax or Experian report looks wrong, send us both PDFs and a short timeline. We will tell you plainly whether there is a consumer dispute worth running, or whether free hardship and counselling pathways should come first.
MyCRA Lawyers is a specialist credit repair law firm. Have your Equifax and Experian report PDFs ready and reach us through our contact form, call 1300 667 218 or 07 3124 7133, or book a 15-minute credit repair intro call. Postal: PO Box 169, Aspley QLD 4034. We quote fixed fees in writing after we assess the file, and we will tell you plainly if a listing looks like a wait-out rather than a viable dispute. On consumer defaults accepted after initial assessment, our independently audited success rate is 91.6%. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. No law firm can promise every listing will come off, and we don’t.
Not ready to talk yet? Pull both free reports and start with a free credit file analysis at app.FixMyBadCredit.com.au. For the bigger picture of how listings are challenged, read our credit repair lawyers Australia guide.
Frequently asked questions
Can I dispute a credit default if I receive Centrelink?
Yes. Credit reporting correction rights do not depend on whether your income is from wages or income support.
Can I ask for hardship while on JobSeeker or a pension?
Yes. Licensed credit providers must consider financial hardship requests for consumer credit. Ask in writing and keep the response.
Do I still get free Equifax and Experian reports on benefits?
Yes. Australians can get a free report from each bureau every three months regardless of benefit status.
Will fixing my credit file guarantee a home loan on Centrelink income?
No. A cleaner file helps the credit assessment. Lenders still decide serviceability under their own policies.
Where should I get free help with debts while on income support?
Start with the National Debt Helpline on 1800 007 007. AFCA and the OAIC are for disputes once you have used a firm’s internal process where required.
General information only. Not legal advice for your circumstances. Liability limited by a scheme approved under Professional Standards Legislation.

Leave A Comment