
Updated 6 November 2026. By Graham Doessel.
Separation is emotional enough without discovering a joint card default on Equifax six months later. Credit reporting does not care who “was supposed to pay.” It cares what was disclosed. Pull both free reports early and keep copies.
Joint facilities and personal applications
Joint accounts can generate enquiries and defaults that follow both parties. New personal applications after separation can create enquiry clusters if you are scrambling for housing. Pause discretionary hard pulls until you know what both bureaus show.
First fortnight checklist
- Free Equifax and Experian reports for you (and encourage your former partner to do the same)
- List joint vs individual accounts
- Change addresses with creditors in writing
- Document who agreed to pay what
- Dispute identity errors immediately
Related: finance before romance, wrong address defaults, cornerstone.
Talk to MyCRA Lawyers
Have both Equifax and Experian PDFs ready and reach us through our contact form, call 1300 667 218 or 07 3124 7133, or book a 15-minute credit repair intro call. Postal: PO Box 169, Aspley QLD 4034. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. Free supports: bureau access every three months, AFCA for members, OAIC, National Debt Helpline 1800 007 007.
Full framework: credit repair lawyers Australia.
Putting the advice to work
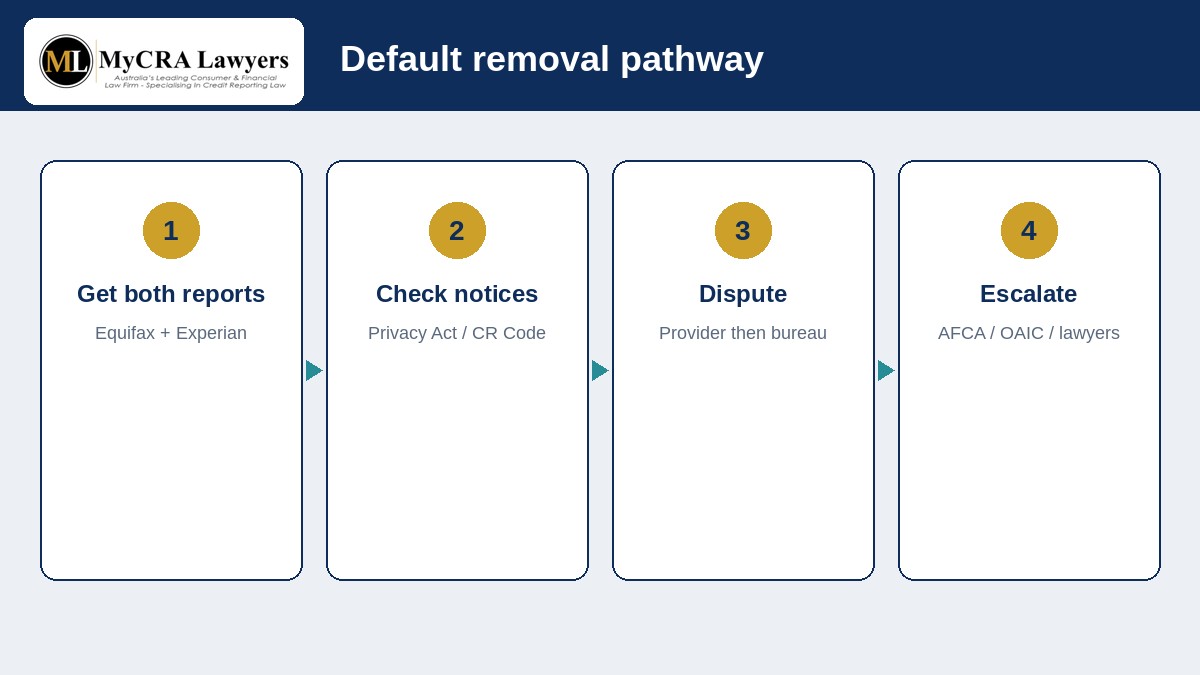
Pull free Equifax and Experian consumer credit reports every three months (OAIC). After a refusal, ask about free access tied to that decision. Save PDFs. Compare identity data, defaults, serious credit infringements, judgments, enquiries and repayment history information. Write a dated chronology before you phone anyone angry. Brokers can read credit repair for mortgage brokers for the deal-saving view.
Dispute clear errors in writing with the credit provider, then use bureau processes where required. AFCA is free for eligible consumers complaining about members after IDR. OAIC pathways may fit some credit reporting privacy issues. Pause new hard enquiries while triage runs. If deadlines are tight or facts are contested, get a legal assessment rather than guessing.
Equifax and Experian remain the practical pair
Australia’s consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, so treat illion as historical context, not a current third bureau you must order separately. Scores will not match. Free consumer credit reports are available every three months (OAIC). After a credit refusal, ask about free access tied to that decision. Save PDFs, not only score dials from an app.
When you dispute, start with the credit provider that disclosed the information in most listing cases, then follow bureau processes as required. Keep a dated chronology. Attach notices, hardship emails, payment proof and identity documents. AFCA is free for eligible consumers complaining about members after internal dispute resolution. OAIC pathways may fit some credit reporting privacy complaints. The National Debt Helpline on 1800 007 007 helps with budgeting and hardship conversations outside a law firm. If a collector is leaning on you, know your rights against debt collector harassment. If you want the detail first, read how it works.
How MyCRA scopes files like this
Have both bureau PDFs and your goal date ready, then reach us through our contact form. Call 1300 667 218 or 07 3124 7133, or book a 15-minute intro call. Postal: PO Box 169, Aspley QLD 4034. We quote fixed fees in writing after assessment. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. From time to time we run a Money Back Guarantee offer on listings with certain creditors. Which creditors it covers changes, so ask us if one is running. We will say if a listing looks like a wait-out rather than a viable dispute.
Read the wider framework on our credit repair lawyers Australia cornerstone, and use free analysis at app.fixmybadcredit.com.au once you have the PDFs.
Mistakes to avoid while you sort this out
- Applying to multiple lenders the morning after a decline
- Paying solely because someone promised the listing would vanish
- Disputing only by phone and keeping no written trail
- Checking one bureau and assuming the other matches
- Hiring anyone who promises removal on every file (no one can. When we run a Money Back Guarantee offer, it refunds your professional fees if a listing is not removed, but it does not promise the result)
- Ignoring repayment history grids because there is no default yet
Most of those mistakes are process failures. A calm fortnight with both free reports, a chronology, and a clear DIY-or-lawyer decision beats a month of panic enquiries that only deepen the problem on Equifax and Experian.
Broker and timing realities
Panels grade listings, enquiry patterns and serviceability, not effort. If a settlement or auction date is close, say so early. Some accepted consumer defaults move in days; escalations and contested notice fights take longer. Do not bet a deposit on a miracle wipe. Pause discretionary hard pulls, brief the broker honestly, and choose AFCA, OAIC or legal help based on evidence rather than Facebook tips.
Useful companions across this series include the pre-loan checklist, default removal guide, and AFCA vs OAIC.
FAQ
Can I remove a joint default because my ex agreed to pay?
A private agreement does not automatically correct credit reporting. Compliance and accuracy still govern listings.
Should I apply for new credit to rebuild quickly?
Only with a plan. Random applications often deepen enquiry damage.
General information only. Not legal advice for your circumstances. Liability limited by a scheme approved under Professional Standards Legislation.

Leave A Comment