
Updated 12 October 2026. By Graham Doessel.
A multi-million-dollar penalty against a bureau is a consumer-rights signal. Bureau products change. Your listings are what lenders underwrite.
Hi, I’m Graham. People still forward me glossy “your score improved” emails while a default sits untouched on the PDF a bank actually reads. That gap is how Credit Prison stays locked.
What the Equifax penalty story means now
Past Federal Court action against Equifax over misleading credit-score representations is a reminder that consumer-facing score products and the underlying credit reporting information are not the same thing. Always download the full report. Compare Equifax with Experian (which includes former illion consumer data from 1 April 2026).
Your rights that still matter
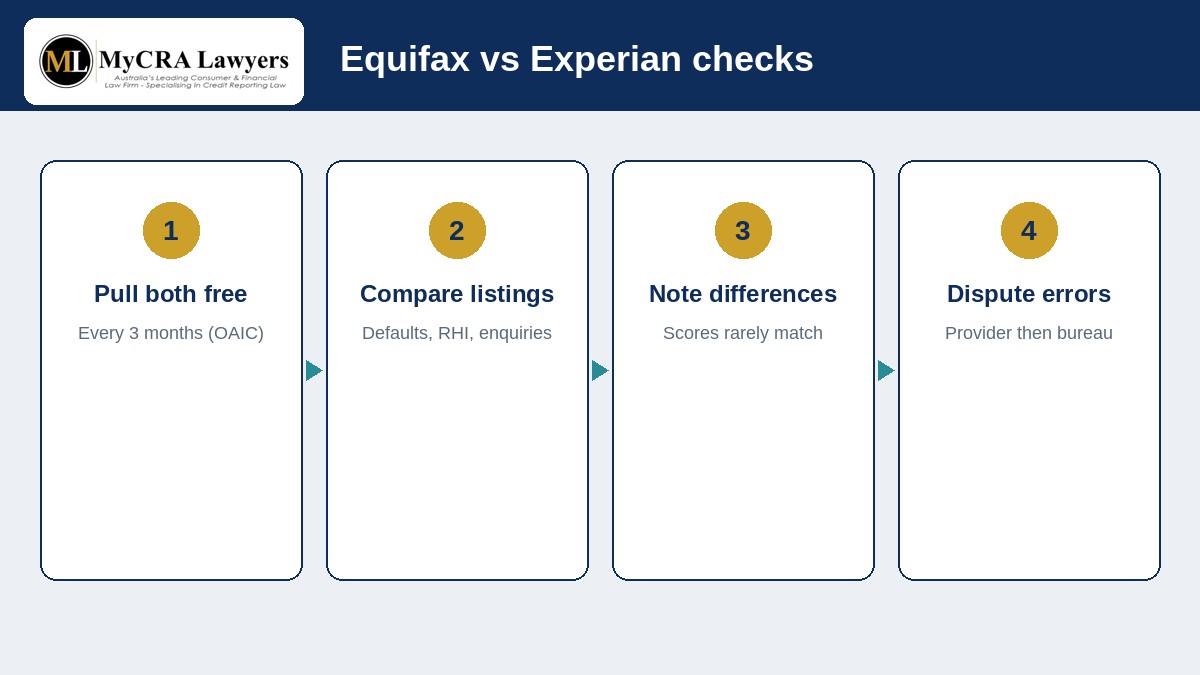
- Free consumer credit report every three months (OAIC)
- Free access after a credit refusal within 90 days, or after a correction
- Correction rights for inaccurate, incomplete, irrelevant or out-of-date credit reporting information
- Complaints to the provider, AFCA (where eligible), and OAIC for privacy issues
Framework: credit repair lawyers Australia. Free reports guide: how to get your free credit report.
On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees quoted before you start. Selected matters include a Money Back Guarantee on the published terms.
Free analysis: app.fixmybadcredit.com.au.
Don’t spend another month stuck in Credit Prison. Call our credit repair lawyers on 1300 667 218 or book a 15-minute intro call at https://mycralawyers.com.au/15min-credit-repair-intro-call/ . If we think your chances are low, we’ll tell you straight.
Bureau penalties and your dispute rights
When a credit reporting body is penalised for misleading conduct, it does not auto-correct your file. It does underline that credit reporting is regulated and that consumers can insist on accurate information. Use the same fundamentals: both free reports every three months, provider disputes, bureau processes, AFCA or OAIC where they fit. Late-payment marks are explained in understanding repayment history information (RHI).
If your listing looks wrong, the pathway is still evidence-led. Do not wait for a news cycle to fix a default that is blocking a home loan. Judgments work differently, and we cover them in how to remove a court judgment from your credit file.
Equifax vs Experian · your rights · cornerstone.
Equifax and Experian: always both
Australia’s consumer credit reporting bodies are Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, so you do not need a separate illion report today. Scores rarely match. Free consumer reports are available every three months (OAIC). After a refusal, ask about free access tied to that decision. Save PDFs, not only score dials.
A simple cleanup order
- Identity and contact data
- Defaults and serious credit infringements
- Judgments
- Enquiries
- Repayment history information
- Hardship flags
Dispute clear errors before you generate new hard enquiries. For broker deals, pause lodgement until the triage is honest. Use app.fixmybadcredit.com.au for a free file analysis once you have the PDFs.
What “good enough” looks like before you apply
You do not need a perfect file. You need an honest map of what lenders will see on Equifax and Experian, a plan for anything non-compliant or incorrect, and enough discipline to stop adding hard enquiries while that plan runs. Brokers would rather wait two weeks for a clean story than inherit four declines.
If a listing is lawful and must age, say so early. If it is challengeable, gather notices and chronologies before you phone the creditor angry. Measured files get better outcomes than chaotic ones.
Internal links worth keeping open: free credit reports, default removal guide, and the credit repair lawyers Australia cornerstone.
Free reports are the starting line
Under Australian credit reporting rules, a credit reporting body must give you a free consumer credit report once every three months (OAIC). You can also seek free access after a credit refusal within the past 90 days, or after a correction. Get Equifax and Experian. Experian absorbed illion’s consumer bureau from 1 April 2026, treat illion as history, not a current third bureau you must pull separately.
Store PDFs somewhere durable. Portal links expire. Score dials without listings are not enough for a dispute or a broker pack.
Common mistakes that keep people in Credit Prison
- Applying again the morning after a decline
- Paying a default because a collector said it would “come off”
- Hiring the loudest repair advert without checking fees or practising status
- Disputing by phone only and keeping no chronology
- Checking one bureau and assuming the other matches
- Ignoring RHI grids because there is no default yet
Most of those mistakes are fixable with process. Start with both free reports, then pick DIY, AFCA/OAIC, or a law firm based on evidence and deadlines, not panic.
Putting it into practice this month
Start with both free Equifax and Experian consumer credit reports. Under OAIC guidance you can access a free consumer credit report from each credit reporting body once every three months, and you should also ask about free access after a credit refusal or after a correction. Save the PDFs. Compare identity details, defaults, serious credit infringements, judgments, enquiries and repayment history information side by side.
Next, write a dated chronology for anything that looks wrong: notices received or not received, hardship emails, payments, address changes, and collector contact. Send a clear written dispute to the credit provider that disclosed the information, attach your evidence, and diary the response timeframes under the Privacy (Credit Reporting) Code. Use the bureau dispute process where required. If the firm is an AFCA member and internal dispute resolution fails, AFCA is free for eligible consumers. OAIC pathways may fit some credit reporting privacy complaints. The National Debt Helpline on 1800 007 007 remains available for budgeting and hardship conversations. Here is how our credit repair process works.
If a broker deadline is close, a judgment or clearout is involved, or the creditor contests the facts, get a legal triage rather than spraying new hard enquiries across lenders. Email docs@mycralawyers.com.au, call 1300 667 218, or book a 15-minute intro call. Read the full framework on our credit repair lawyers Australia cornerstone. On consumer defaults accepted after initial assessment, our success rate is 91.6%, independently audited by a chartered accountant. Our own records show 29.4% of defaults are removed within 7 days. Fixed fees in writing. Selected matters include a Money Back Guarantee on published terms. Postal address: PO Box 169, Aspley QLD 4034.
FAQ
Does a bureau fine delete my default?
No. Penalties for misleading conduct do not automatically clear individual consumer listings.
Should I ignore score apps?
Use them as a trend hint only. Disputes need full report detail.
How often are free reports available?
Once every three months per credit reporting body, plus specified extra free-access situations (OAIC).
Which bureaus should I check in 2026?
Equifax and Experian.
When should I call MyCRA?
When listings look wrong, notices were missed, or a lending deadline is close, start with the free analysis or intro call.
This is general information, not legal advice. Liability limited by a scheme approved under Professional Standards Legislation.
MyCRA Lawyers | Australia-wide | 1300 667 218 | docs@mycralawyers.com.au | PO Box 169, Aspley QLD 4034

Leave A Comment